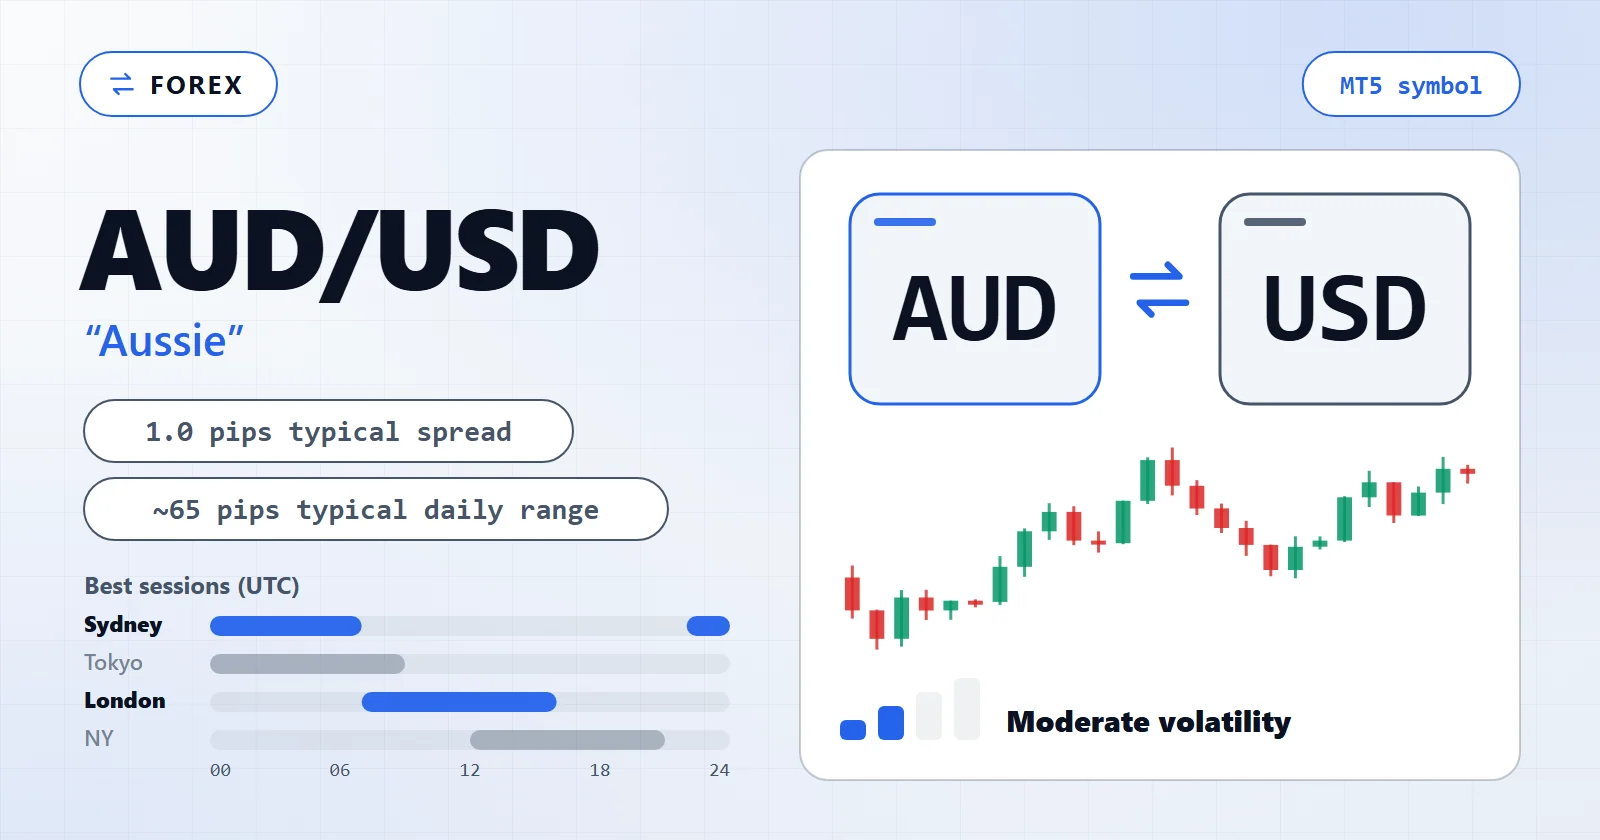
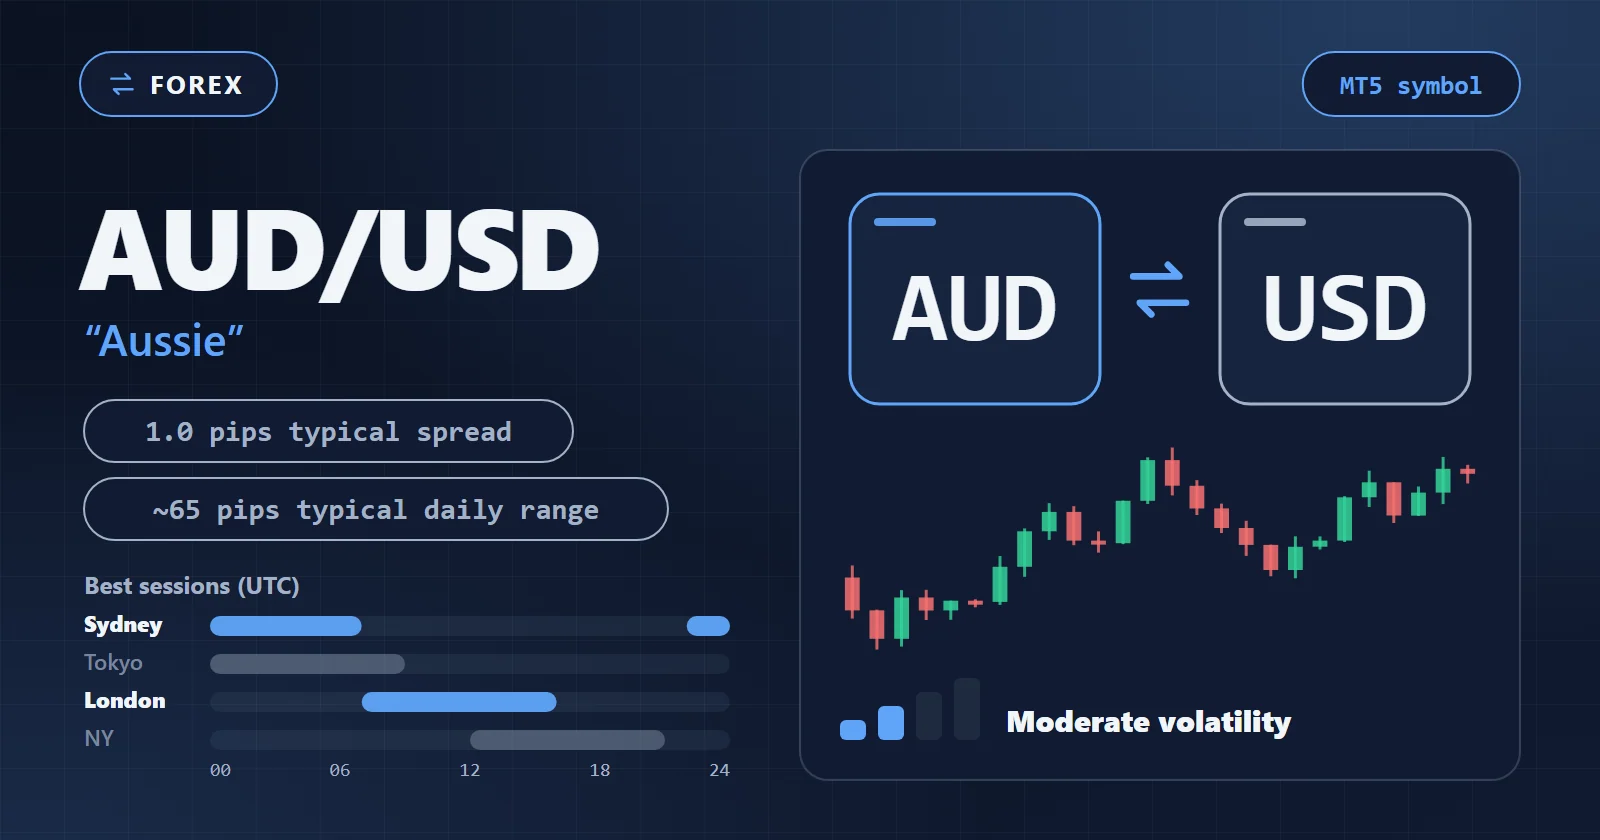
AUD/USD — the “Aussie” — is the commodity major and the pair most retail systems reach for when they want a clean risk barometer. The first thing to decide is whether your strategy wants that character or merely tolerates it. A live Sydney session and long, commodity-driven trends are an edge for trend and breakout EAs. The pair’s habit of falling with the equity market is a tail a system ported from EUR/USD never has to price. Pick the pair to the strategy, not the other way round.
This page covers what AUD/USD gives an automated strategy that EUR/USD does not, the sessions that decide its results, and what it costs. It then covers the failure modes that catch systems moved over from a pure USD major, and how to build and test an AUD/USD EA of your own.
How AUD/USD Behaves: What Aussie Gives an EA
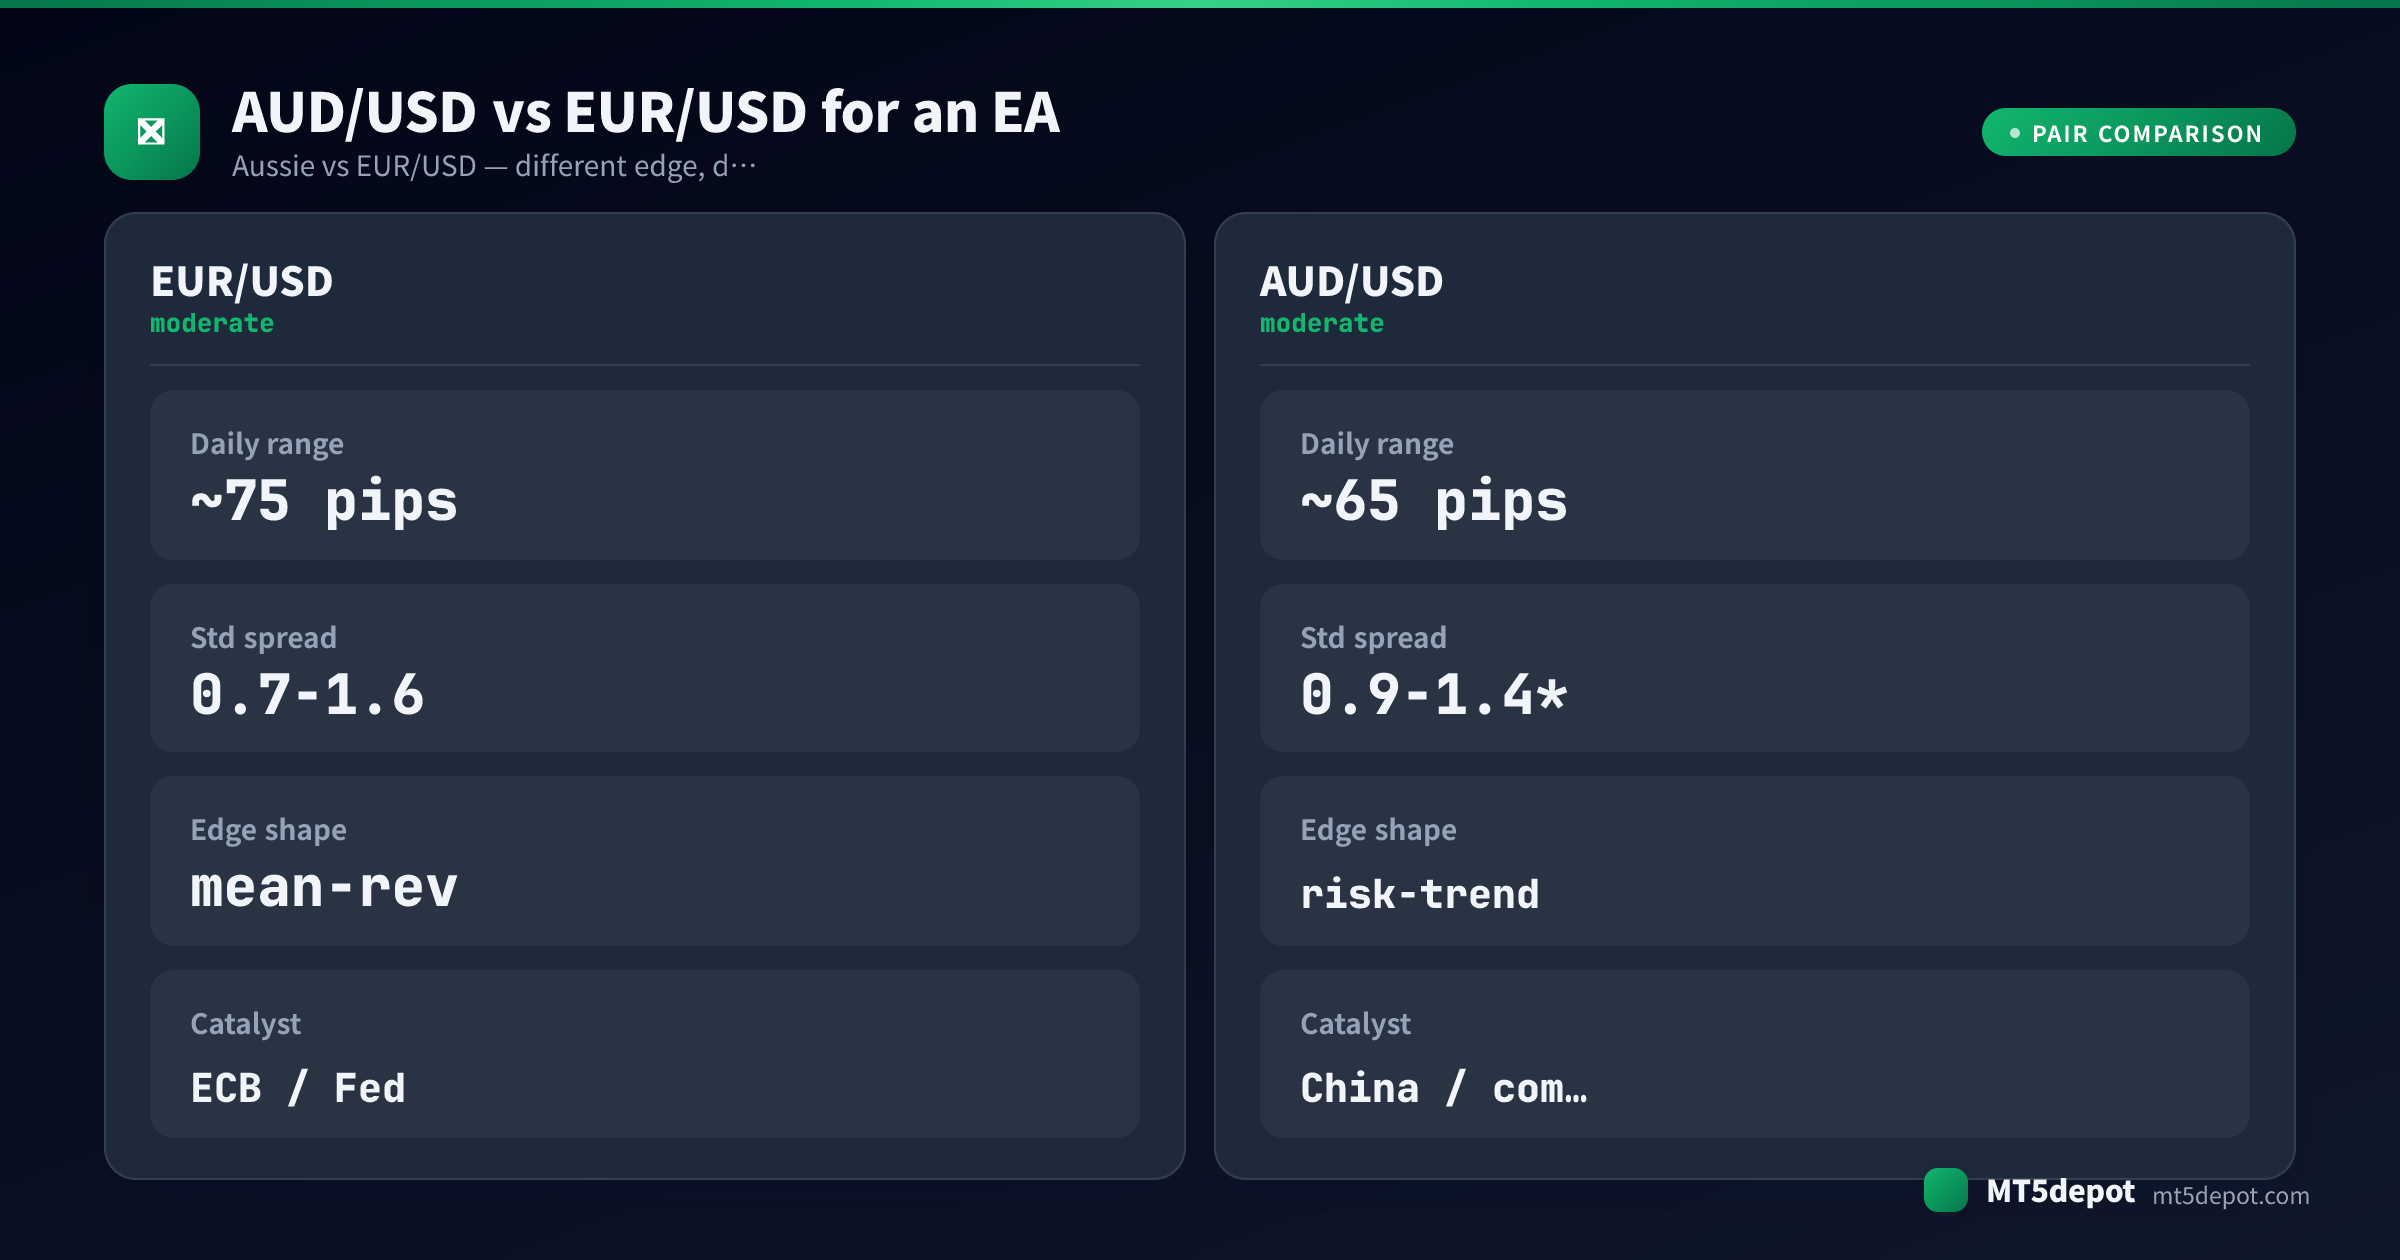
AUD/USD trades a large share of global forex volume and is structurally different from the European majors in one respect that matters for automation. It is a commodity currency, not a pure interest-rate story. Iron ore, coal and Chinese import demand sit underneath the price. That gives it two properties EUR/USD lacks — sustained directional trends and a tight link to global risk appetite — and one liability that follows from them.
For an EA, that character reduces to three properties:
- A live Sydney session. AUD/USD moves on Australian liquidity and regional data in the early-Asian hours (roughly 21:00–24:00 UTC) when European pairs are effectively asleep. That is a genuine, non-obvious edge. A 24-hour trend EA tends to read real signal on Aussie during Sydney, where the same overnight window on EUR/USD is mostly noise that reverses at the London open.
- Commodity-driven trends. Because iron-ore, coal and Chinese-demand cycles move slowly, AUD/USD often produces multi-week directional runs rather than the tight mean-reverting range of a pure USD major. That trend structure is what makes the pair suit momentum systems — the catalyst is a growth story, not a single rate print.
- A risk-barometer tilt. The same commodity backing makes the Aussie a proxy for global risk appetite. It tends to strengthen when growth expectations rise and, critically, to fall with equities when they don’t. That link is an edge for a system that reads the regime and a liability for one that assumes an FX pair only responds to FX news.
The trap for automated strategies is subtle. The commodity trend that looks like a smooth edge on a backtest is the same exposure that gaps down with the stock market in a risk-off event. The backtest rarely spans one. Aussie rewards systems that respect its volatility regime and quietly drains ones that treat it as a slower EUR/USD.
Which EA Strategies Suit AUD/USD?
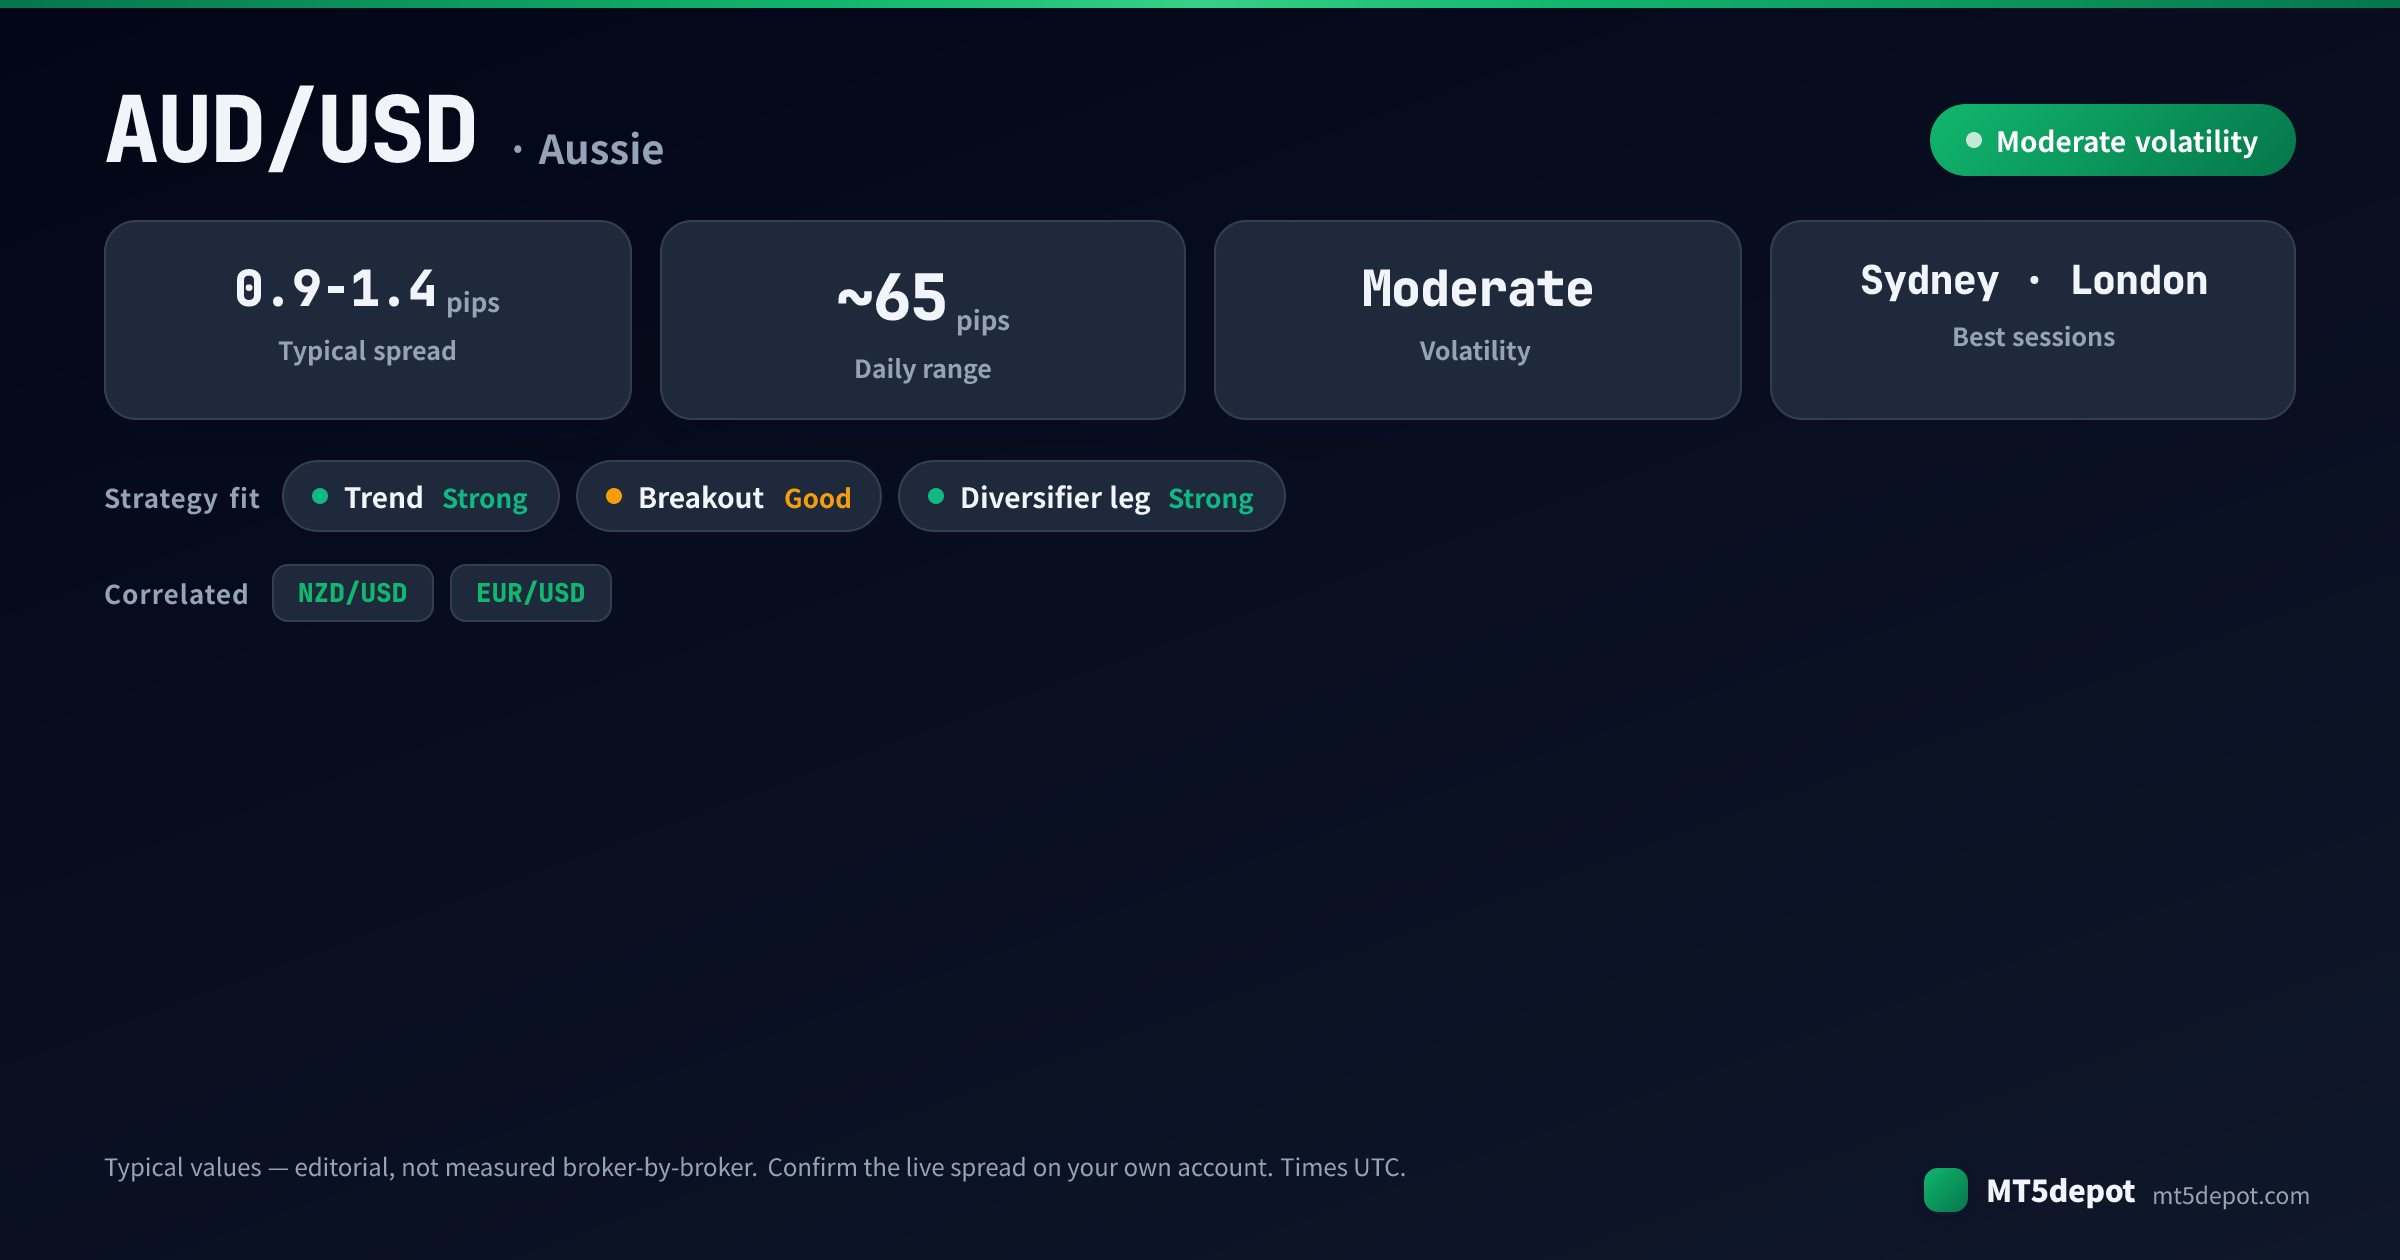
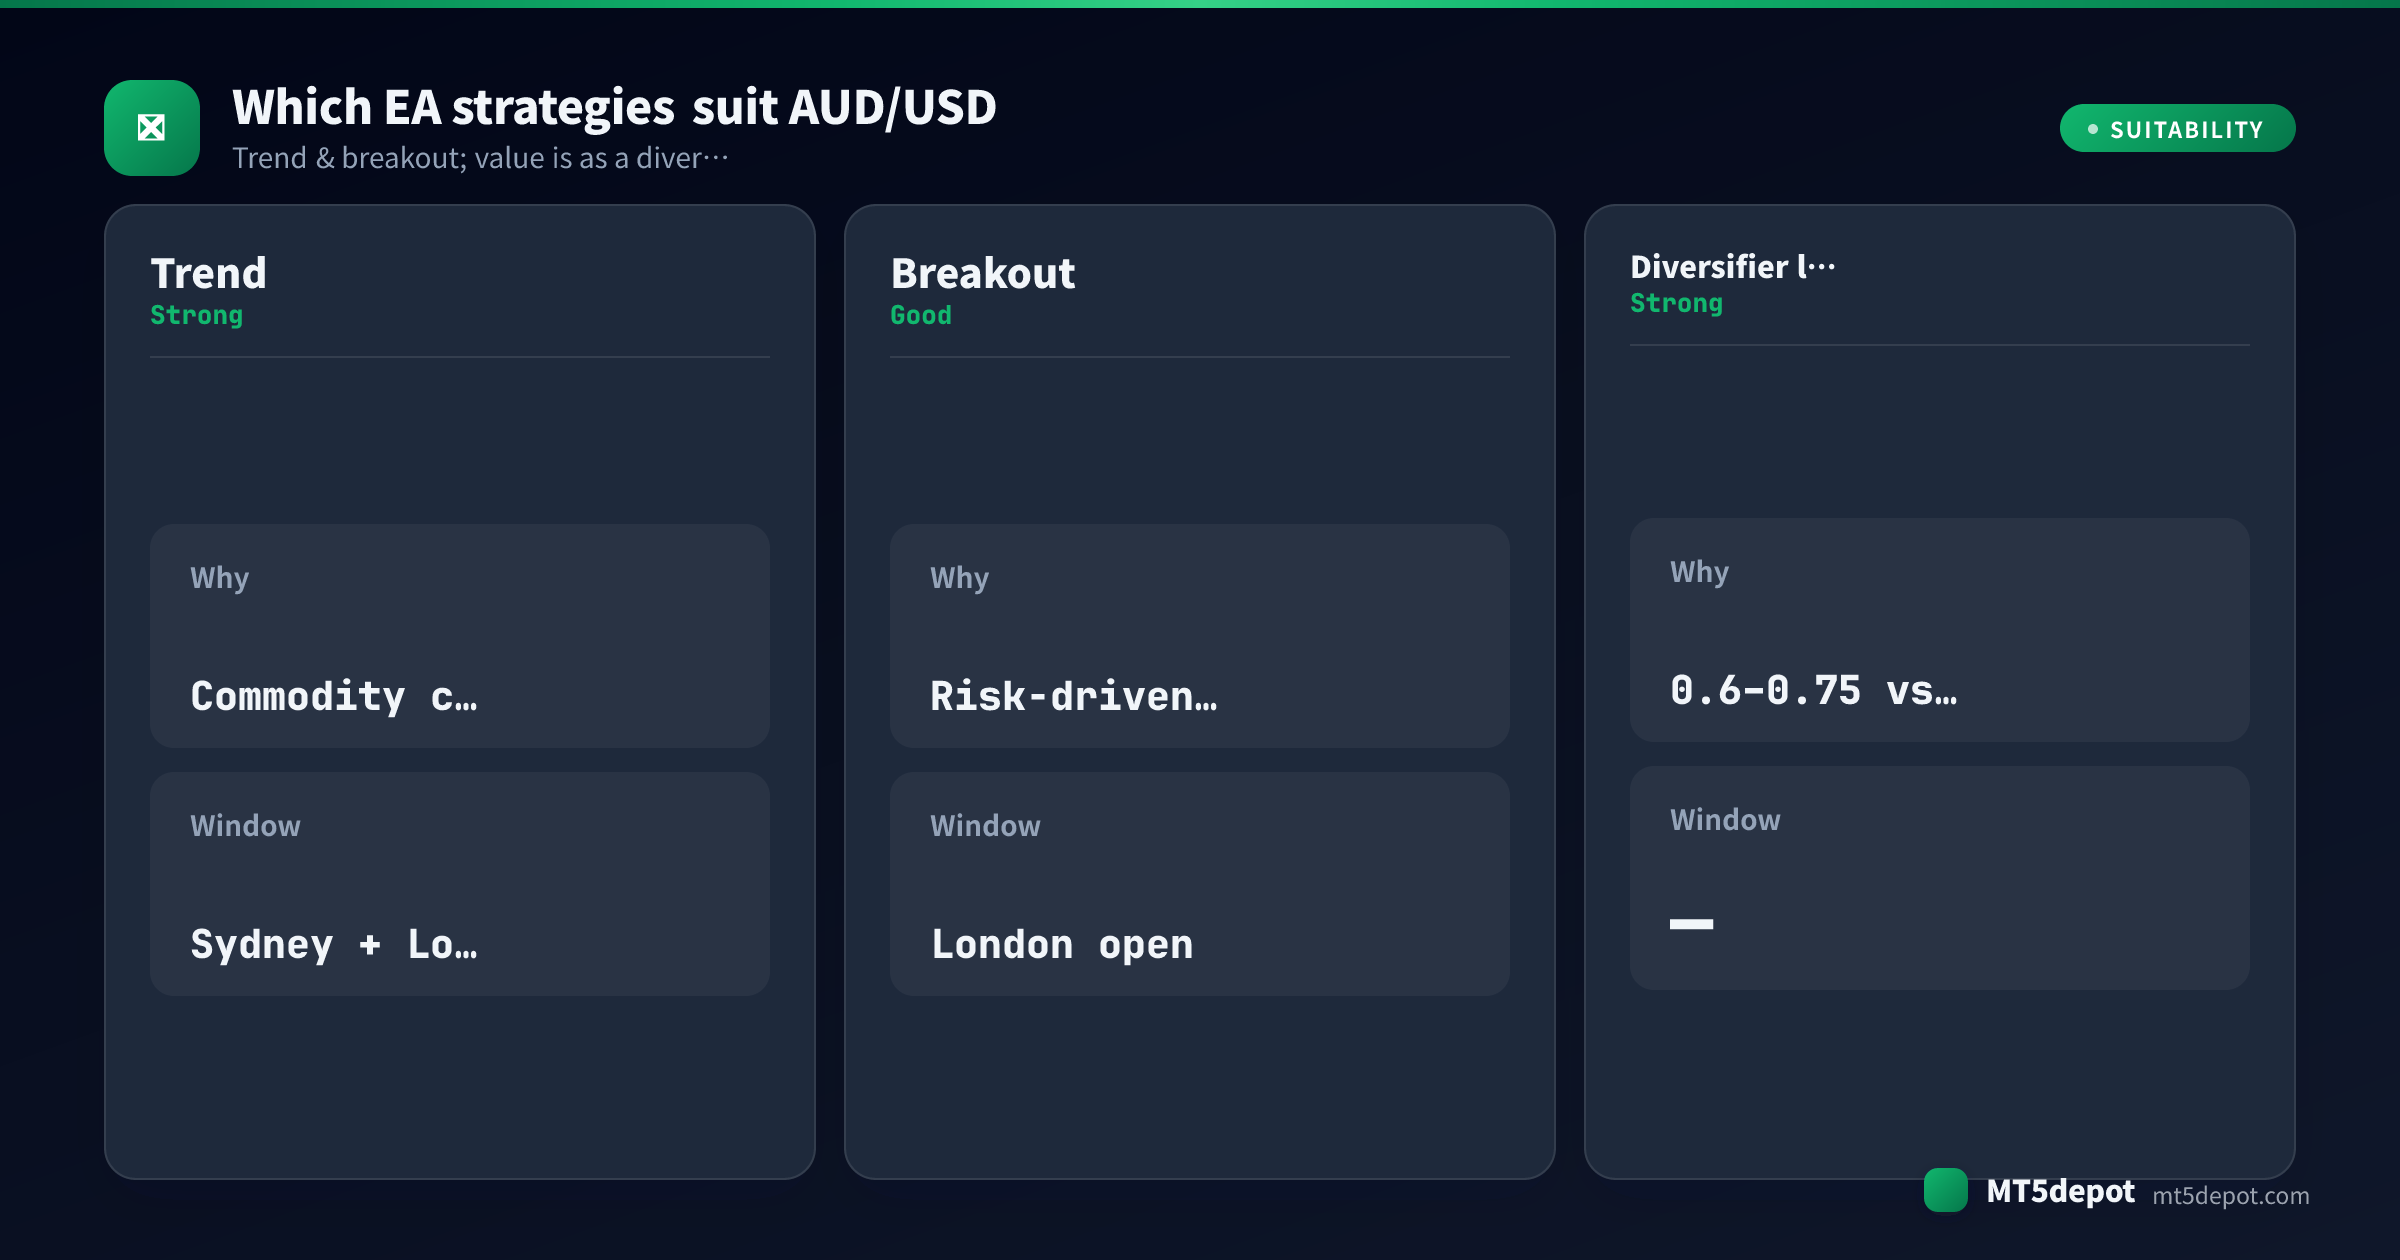
The pair’s profile lists trend and breakout as suitable — but suitability is an editorial assessment, not proof. In our own stock-settings baseline of the Builder’s templates — a single USD/JPY M5 run over one year, default inputs, no optimisation — most finished below a 1.0 profit factor, and the only AUD/USD exposure in it came from one leg of the risk-on basket template, which also finished below 1.0. Almost none cleared the Builder’s own bar at stock settings, so treat any edge on AUD/USD as something your own settings and test have to earn. Look for it in mechanics — session windows, event pauses — not the indicator on the box. What AUD/USD’s character tends to support:
| Strategy | Fit on AUD/USD | Why |
|---|---|---|
| Trend-following | Strong | Commodity and China-demand cycles produce sustained multi-week moves; a momentum system can ride them, and the Sydney-plus-London windows are where they run cleanest. |
| Breakout | Good | Risk-driven ranges resolve into directional moves, often on the London open, which gives an objective level for a pending-order entry rather than a market fill. |
| Diversifier leg | Strong (with a caveat) | AUD/USD’s correlation with EUR/USD typically sits in a moderate band, so a multi-pair portfolio EA could use it as a diversifier — but only if the NZD/USD overlap below is respected, or the “diversification” is an illusion. |
Trend and breakout are the shapes that turn AUD/USD’s commodity structure into an asset; the diversifier role is real but conditional. The practical route is to build one of these shapes yourself. The Builder ships templates that accept AUD/USD and exposes every parameter. Test it (below) before you trust a single number.
Best Trading Hours for AUD/USD EAs
Session structure decides more of an Aussie result than indicator choice does:
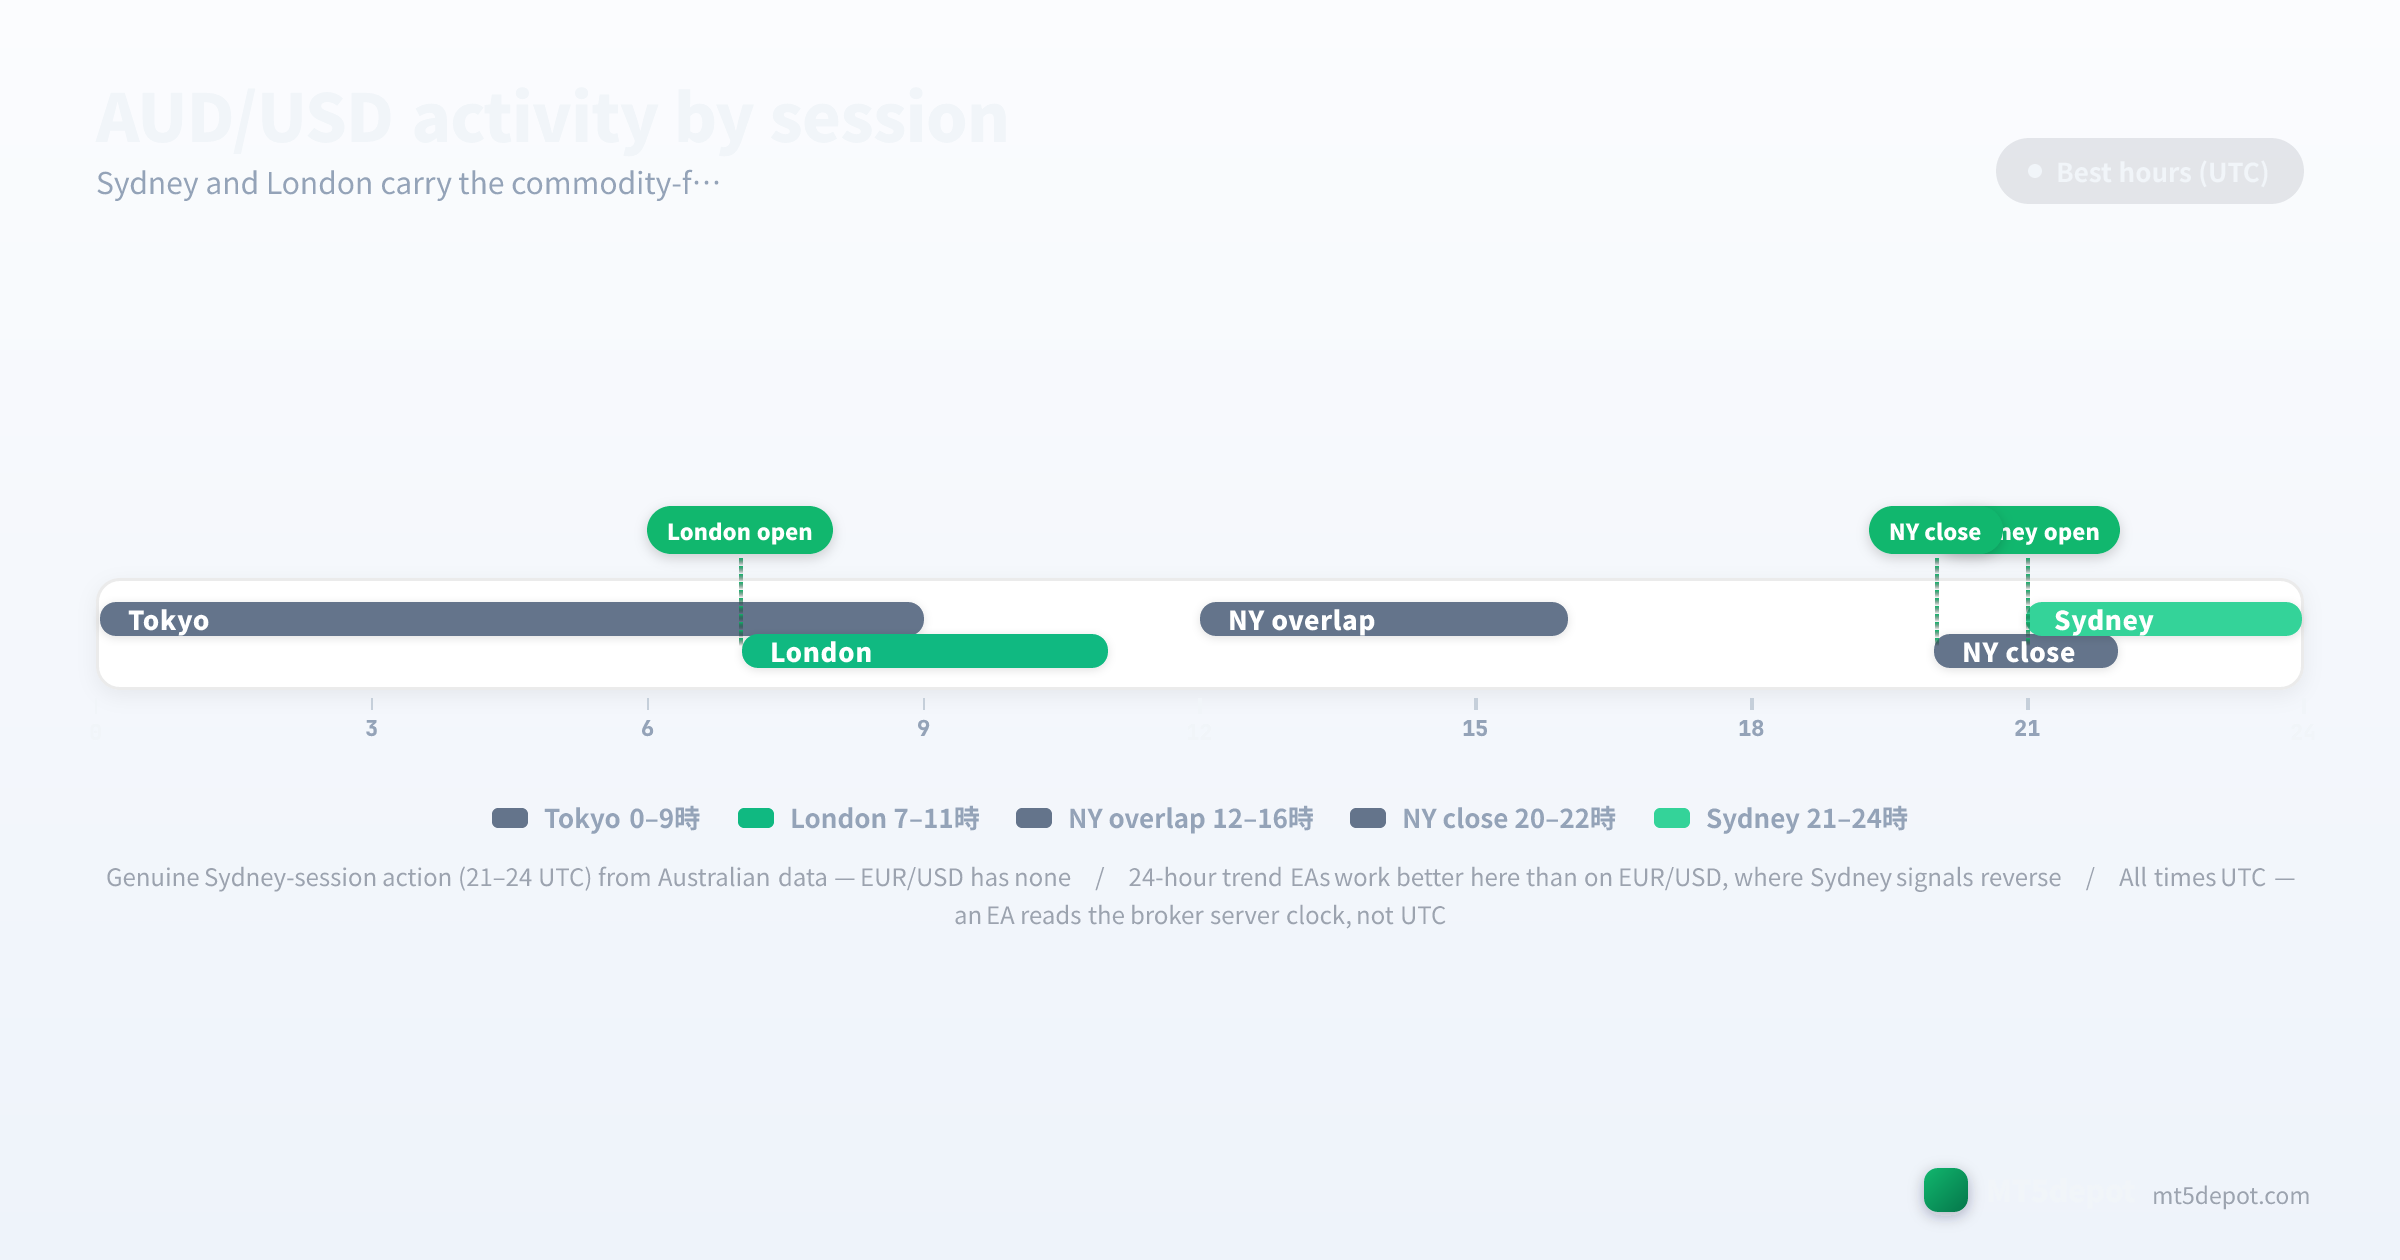
- Sydney session (21:00–24:00 UTC): the pair’s home window and its least-appreciated edge. Australian liquidity and regional data give AUD/USD real range here. This is the one stretch where an overnight signal on this pair is more likely to be trend than noise. That is exactly why a 24-hour trend EA can work on Aussie where it fails on EUR/USD.
- Tokyo hours (00:00–07:00 UTC): Asian flow keeps the pair active, though moves are often continuation of the Sydney lead rather than fresh direction.
- London session (07:00–16:00 UTC): the deepest liquidity of the day and where the cleanest trending and breakout moves tend to resolve; the London open in particular gives breakout systems an objective level.
- Late NY / pre-Sydney (roughly 20:00–21:00 UTC): thin liquidity before the Sydney open, with low-conviction drift; session-quality filters should usually exclude this handover.
EAs that restrict trading to the Sydney-and-London windows often out-perform 24-hour variants on AUD/USD, in our editorial assessment. A session filter here is best treated as part of the strategy definition rather than an optimisation flourish. Two cautions come with it. Scheduled RBA and US releases sit inside the good windows and widen spreads exactly then, so a fast strategy needs a news pause or it pays several times the normal spread at the worst moment. And every clock time above is UTC. An EA reads your broker’s server clock, which is usually not UTC, so a “21:00” Sydney filter shifts silently when you move the EA between brokers on different server timezones. This is the one clock rule for the whole page. Verify it once in MT5’s Market Watch, and every session boundary lines up.
Spreads, Costs, and Execution
AUD/USD is one of the cheaper majors to trade, a touch wider than EUR/USD. The figures below are editorial reference ranges compiled from broker-published standard and raw conditions (updated July 2026), not broker-by-broker measured numbers; our live spread sampling currently covers EUR/USD and a few reference symbols. Confirm the live spread on your own account before you size a fast strategy:
| Account type | Typical AUD/USD spread | Commission | Who it suits |
|---|---|---|---|
| Standard | 0.9 – 1.4 pips | none | swing / trend / breakout EAs |
| Raw / ECN | sub-pip (≈0.2 – 0.5) | $3 – 7 / lot | scalping / high-frequency EAs |
Two cost rules specific to this pair:
- Budget for the data-driven spread spikes. AUD/USD’s standard spread is tight most of the day, but RBA decisions, Australian employment and inflation prints, and US releases can widen it sharply. Unlike a EUR/USD system, an Aussie EA also faces widening around Chinese data and commodity moves that a US-centric news filter may not even list. A fast strategy validated on the calm midday spread is running a different cost model from the one that actually fires around a catalyst.
- The commission is an account property, not a pair property. The same $3–7/lot raw commission applies whether you trade EUR/USD or Aussie; what changes between pairs is the spread on top of it. AUD/USD’s still-tight standard spread makes it viable for swing and trend strategies without a raw account. A scalper on the same pair belongs on raw, so the swap and the spread are known numbers rather than variables.
Risks to Test Before Going Live
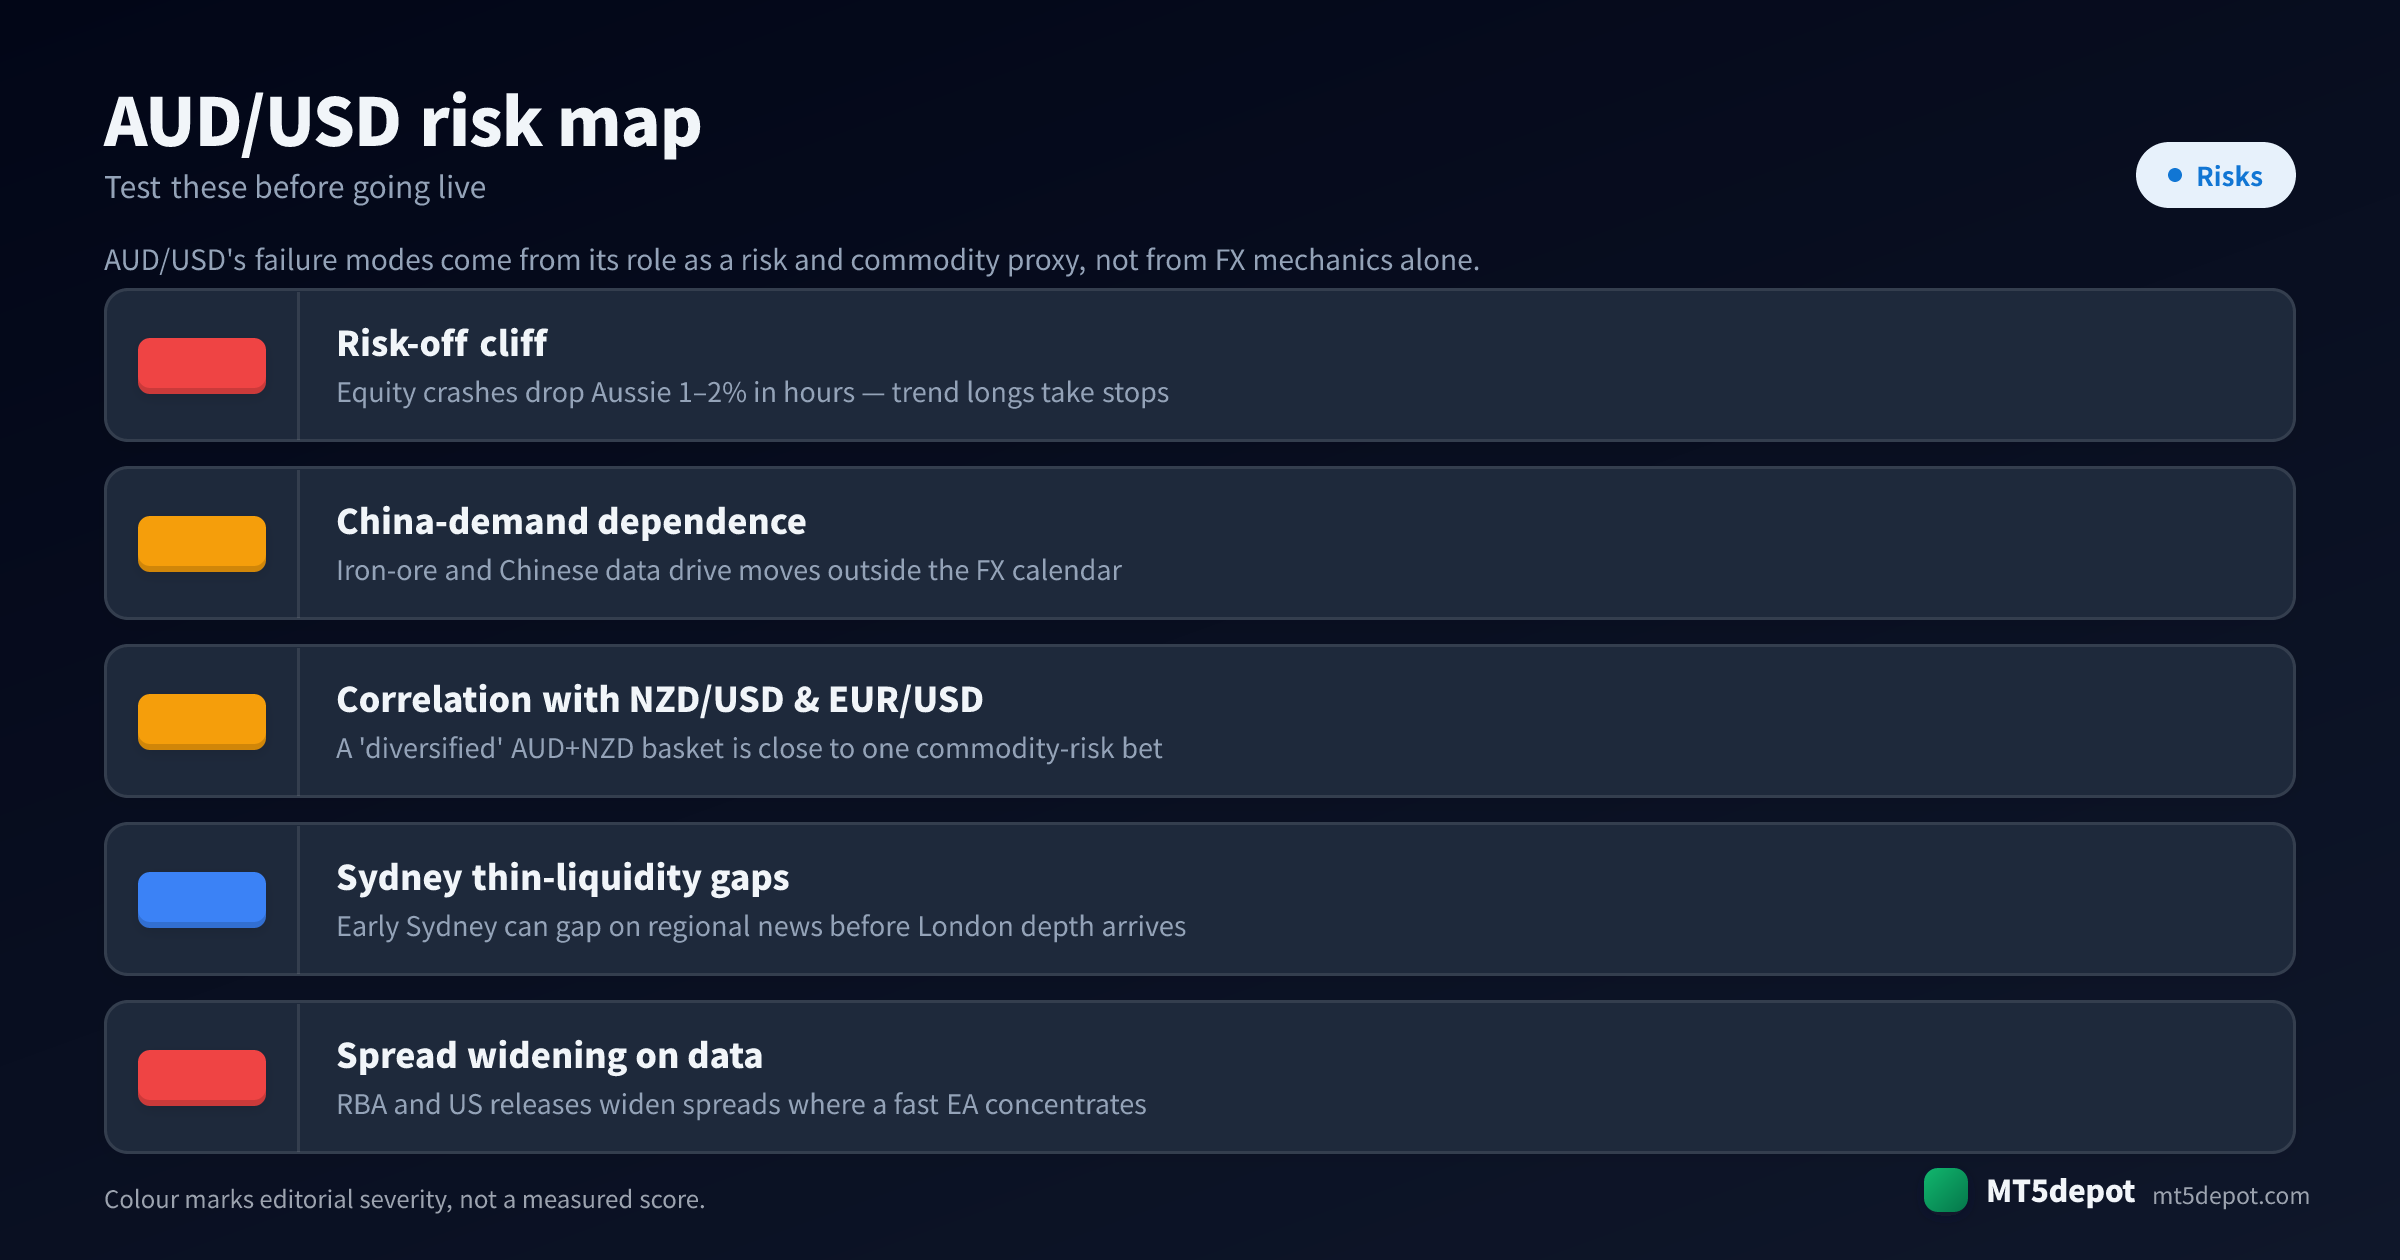
AUD/USD’s failure modes come from its role as a risk and commodity proxy, not from FX mechanics alone — so a generic risk checklist misses them:
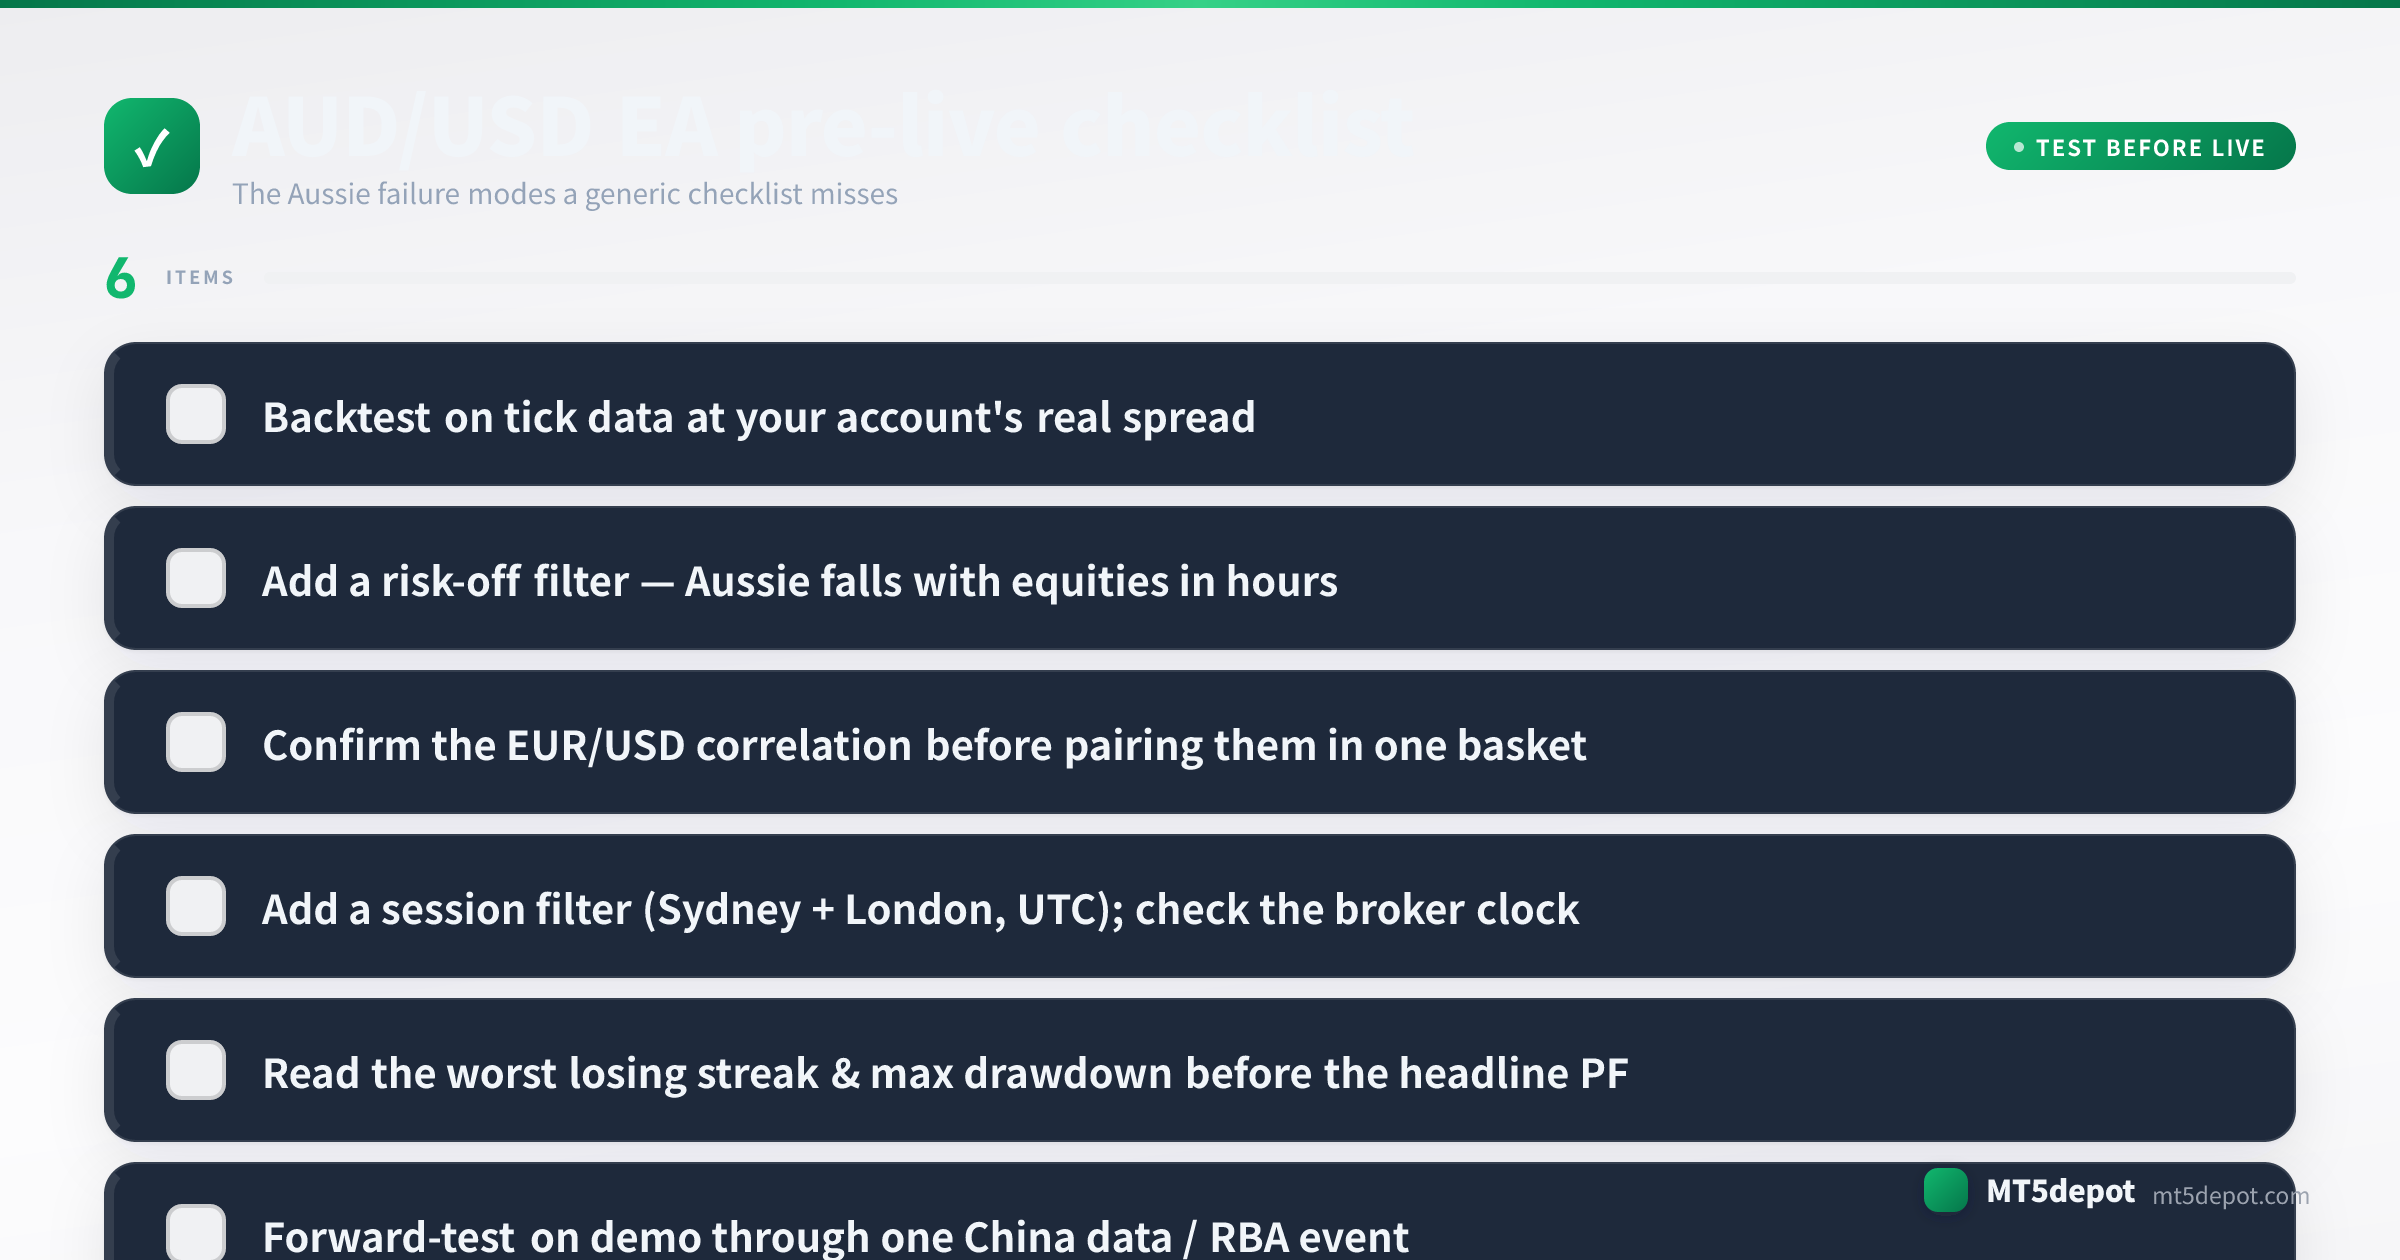
- The risk-off cliff is not an FX event. An equity crash can drop AUD/USD one to two percent in hours, sometimes with no forex-specific catalyst at all, and a trend long that is riding the commodity uptrend takes stops in the reversal. This is the single behaviour a EUR/USD EA never has to model; an Aussie system needs a risk-off or volatility filter, not just a stop.
- China-demand dependence sits outside the FX calendar. Iron-ore prices and Chinese growth or PMI data move AUD/USD as hard as some domestic releases, but many of those prints fall outside the standard economic calendar an EA watches. A news pause tuned only to RBA and US events can leave the strategy exposed to the exact catalyst that moves the pair most.
- Correlation is hidden leverage. AUD/USD moves with NZD/USD, and shares a moderate correlation with EUR/USD. A “diversified” basket of AUD/USD and NZD/USD is close to one leveraged commodity-risk bet rather than a hedge. The correlation stacks your exposure without appearing anywhere in either EA’s risk settings, so confirm how closely the two pairs move together (see volatility) before pairing them in one account.
- Early-Sydney liquidity gaps manufacture false fills. The pair’s home session is also its thinnest opening. Early Sydney can gap on regional news before London-depth liquidity arrives. An unfiltered EA entering at the open can get a fill and a slip that the backtest, built on mid-session ticks, never showed.
How to Test a AUD/USD EA
On AUD/USD, the test is the whole edge. Hold anything you build to the bar set out in the site’s methodology:
- Backtest on tick data at your account’s real spread. Use an every-tick model with the standard-or-raw spread you will actually trade, not the platform default. Include the wider spread that RBA, US and commodity events print, because that is when a fast Aussie EA concentrates its trades. A strategy validated at costs it will never see is a fiction.
- Read the worst losing streak, not the headline profit factor. The max drawdown and the longest run of losing trades tell you the capital and the patience the strategy demands. Budget for the worst streak before you fund it.
- Forward-test on demo through at least one China-data or RBA event. Aussie’s defining risk only shows up around a commodity move, a Chinese release or an RBA decision. A demo window that never spans one — and never spans a risk-off equity day — has not tested the thing that matters most.
- Confirm the server clock before the first live trade. Re-check MT5’s Market Watch time against the UTC session hours above, and re-check it again after any broker migration — a step that is easy to skip and expensive to miss.
Every backtest number this produces is a historical measurement, not a forecast — say so in your own notes, and size for the drawdown you measured rather than the return you hope for.
AUD/USD EAs and Builder Templates
We have not published an AUD/USD backtest of our own, and a EUR/USD result does not carry over to a pair that falls with equities in a risk-off event. The honest route to an Aussie EA is to build and verify one:
- The Builder (open it here) accepts AUD/USD in its trend, breakout and multi-symbol templates. The EA you deploy is built on your own numbers, and the CTA below covers exactly what it produces.
- Portfolio context. Because AUD/USD’s correlation with EUR/USD sits in a moderate band, a multi-pair portfolio EA could use it as a diversifier leg. That holds only if you have first checked its overlap with NZD/USD, and compared the live conditions on your own account against its contract specification before you fund it.
- The concept canonicals. If a term above is unfamiliar, the spread, swap and volatility entries define the mechanics an AUD/USD EA depends on.

