The FTSE 100 — “the Footsie” — is a stock-index CFD, not a currency pair, and it behaves unlike either forex or the equity index most EAs are built against. Its constituents are large, globally-earning companies weighted toward energy majors, miners and banks. That gives the index a currency-and-commodity tilt which catches automated strategies out: it often rises when the pound falls, and it can lurch on an oil headline while the UK data calendar is quiet. The first thing to decide is whether your strategy wants that character — a commodity-led index calmer than the DAX but wired to sterling — or merely tolerates it. A system tuned on GER40 or a US index meets a different animal the moment it touches UK100. Pick the instrument to the strategy, not the other way round.
This page covers what the Footsie gives an automated strategy that forex and the louder indices do not, and the sessions and costs that decide its results. It then covers the failure modes that catch ported systems, and how to build and test a UK100 EA of your own.
How UK100 Behaves: What The Footsie Gives an EA
UK100 tracks the 100 largest companies listed in London, and it is structurally different from both a forex pair and a domestically-driven index. Its catalysts sit outside the FX world an EA was probably designed for, and outside the home-market logic a generic equity strategy assumes.
For an EA, that character reduces to three properties:
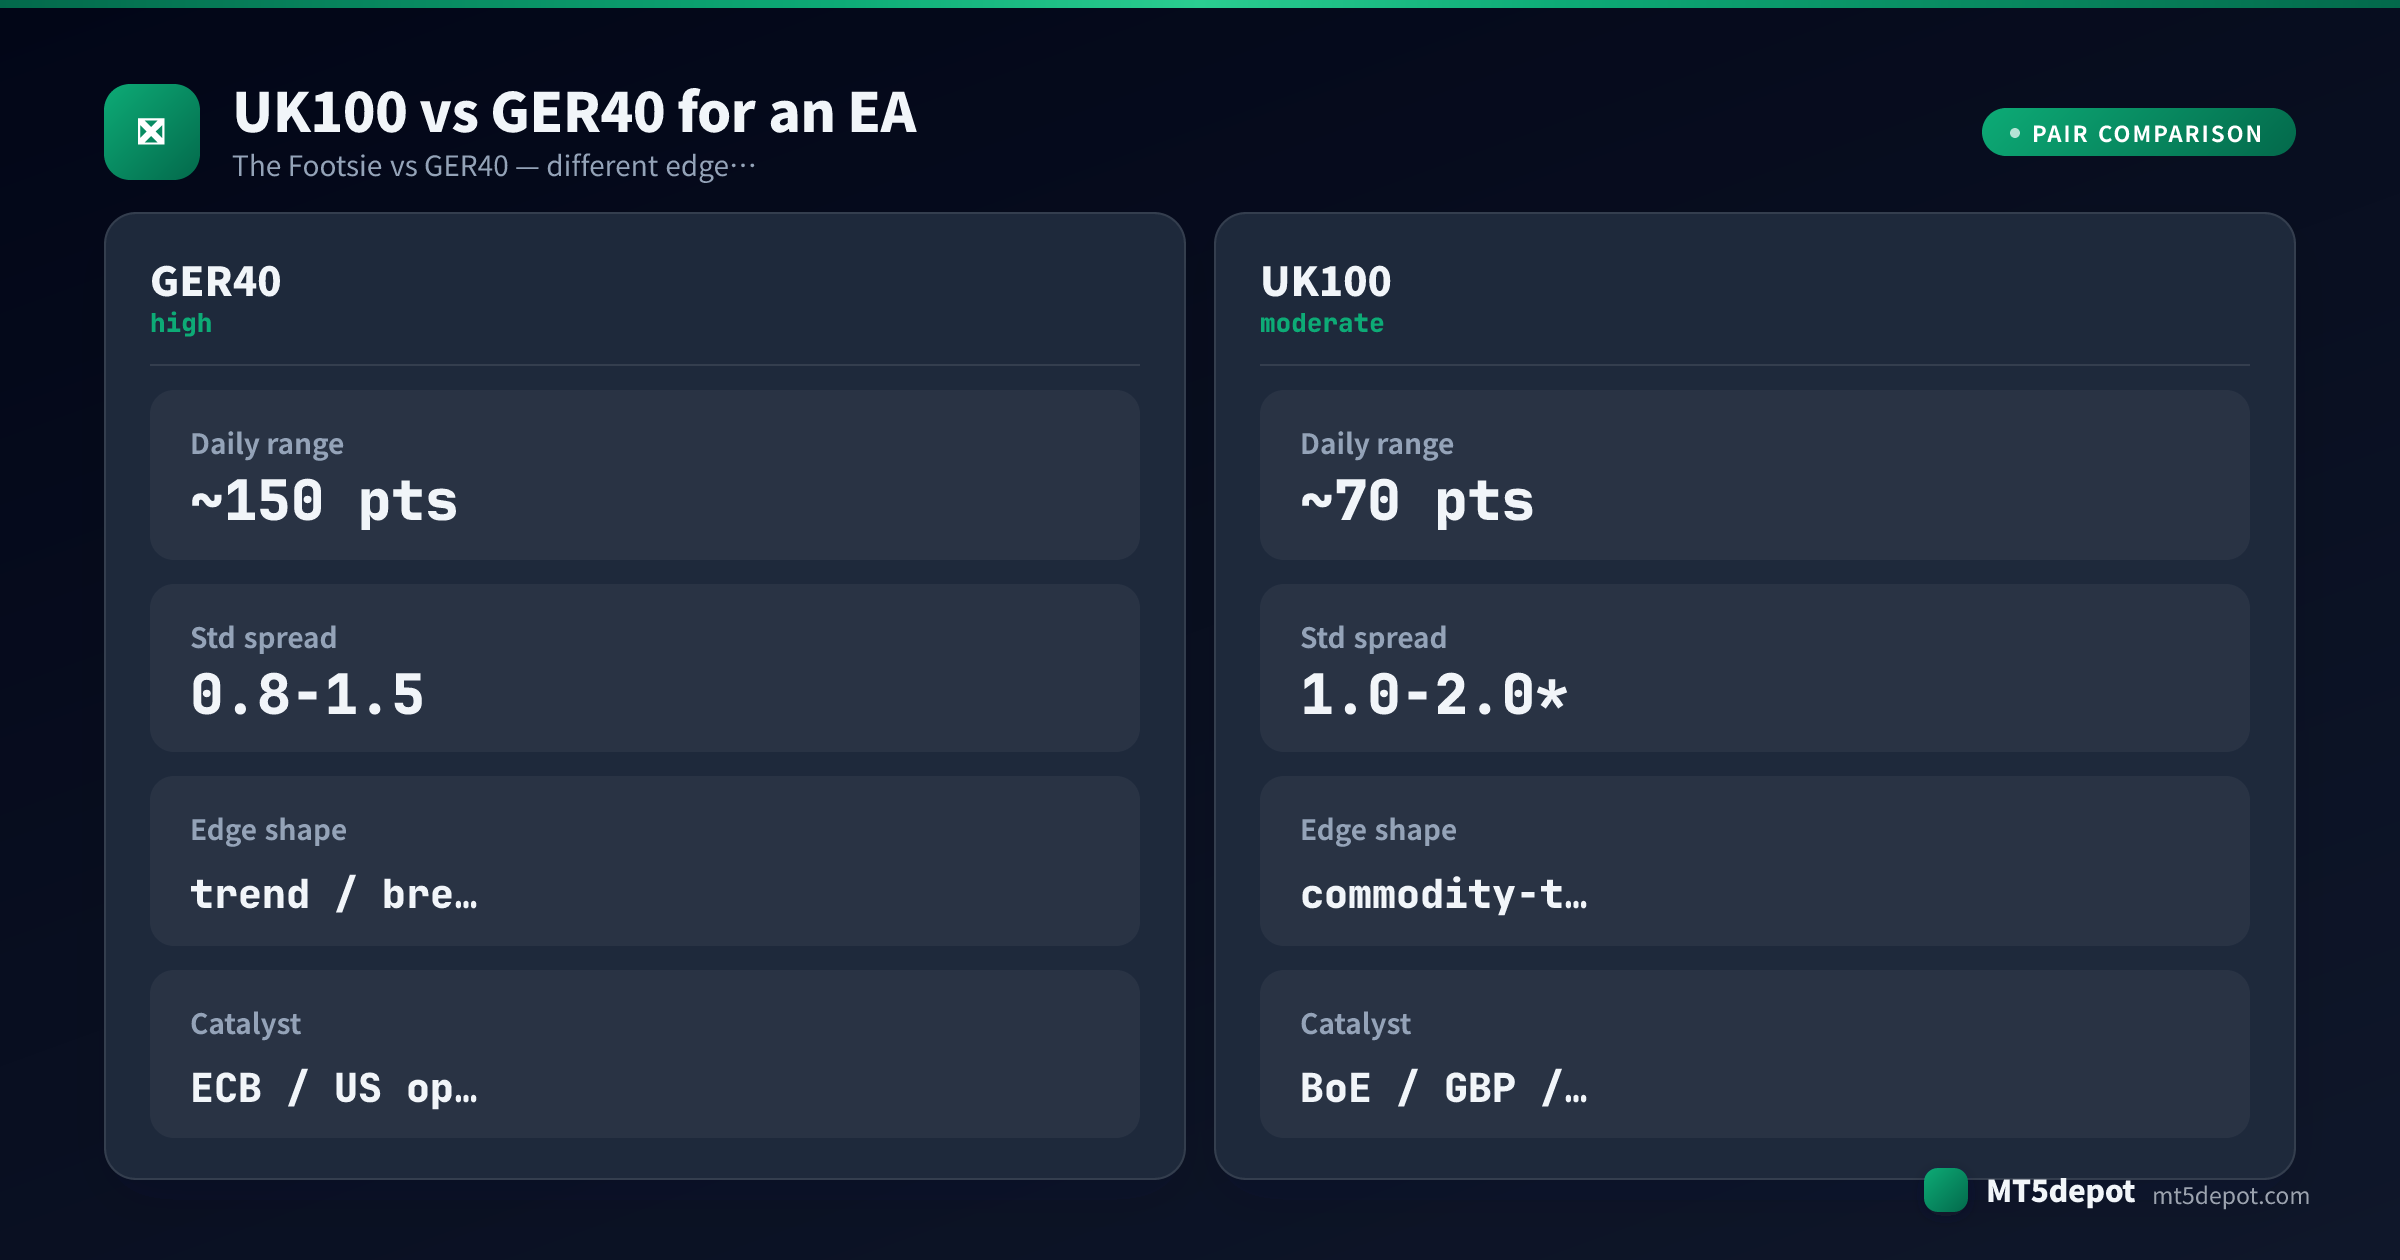
- The inverse-GBP tilt. Roughly three-quarters of FTSE 100 revenue is earned abroad, so a weaker pound inflates those overseas earnings in sterling terms and often lifts the index. That is the opposite of the intuition that a strong domestic currency helps the local market. It is the fact everything else here follows from, and the one most likely to break a strategy that treats UK100 as “the UK stock market”. A price-and-momentum EA reading the index in isolation has no idea a sterling move may be the real driver behind its position.
- A commodity and financials weighting, not a broad tech index. Oil majors and miners carry heavy index weightings, so a move in oil or metals can drive the Footsie as much as any UK data print. An EA that models UK100 as a generic equity index misses that a commodity headline — not an earnings or GDP number — is frequently the catalyst behind a big candle.
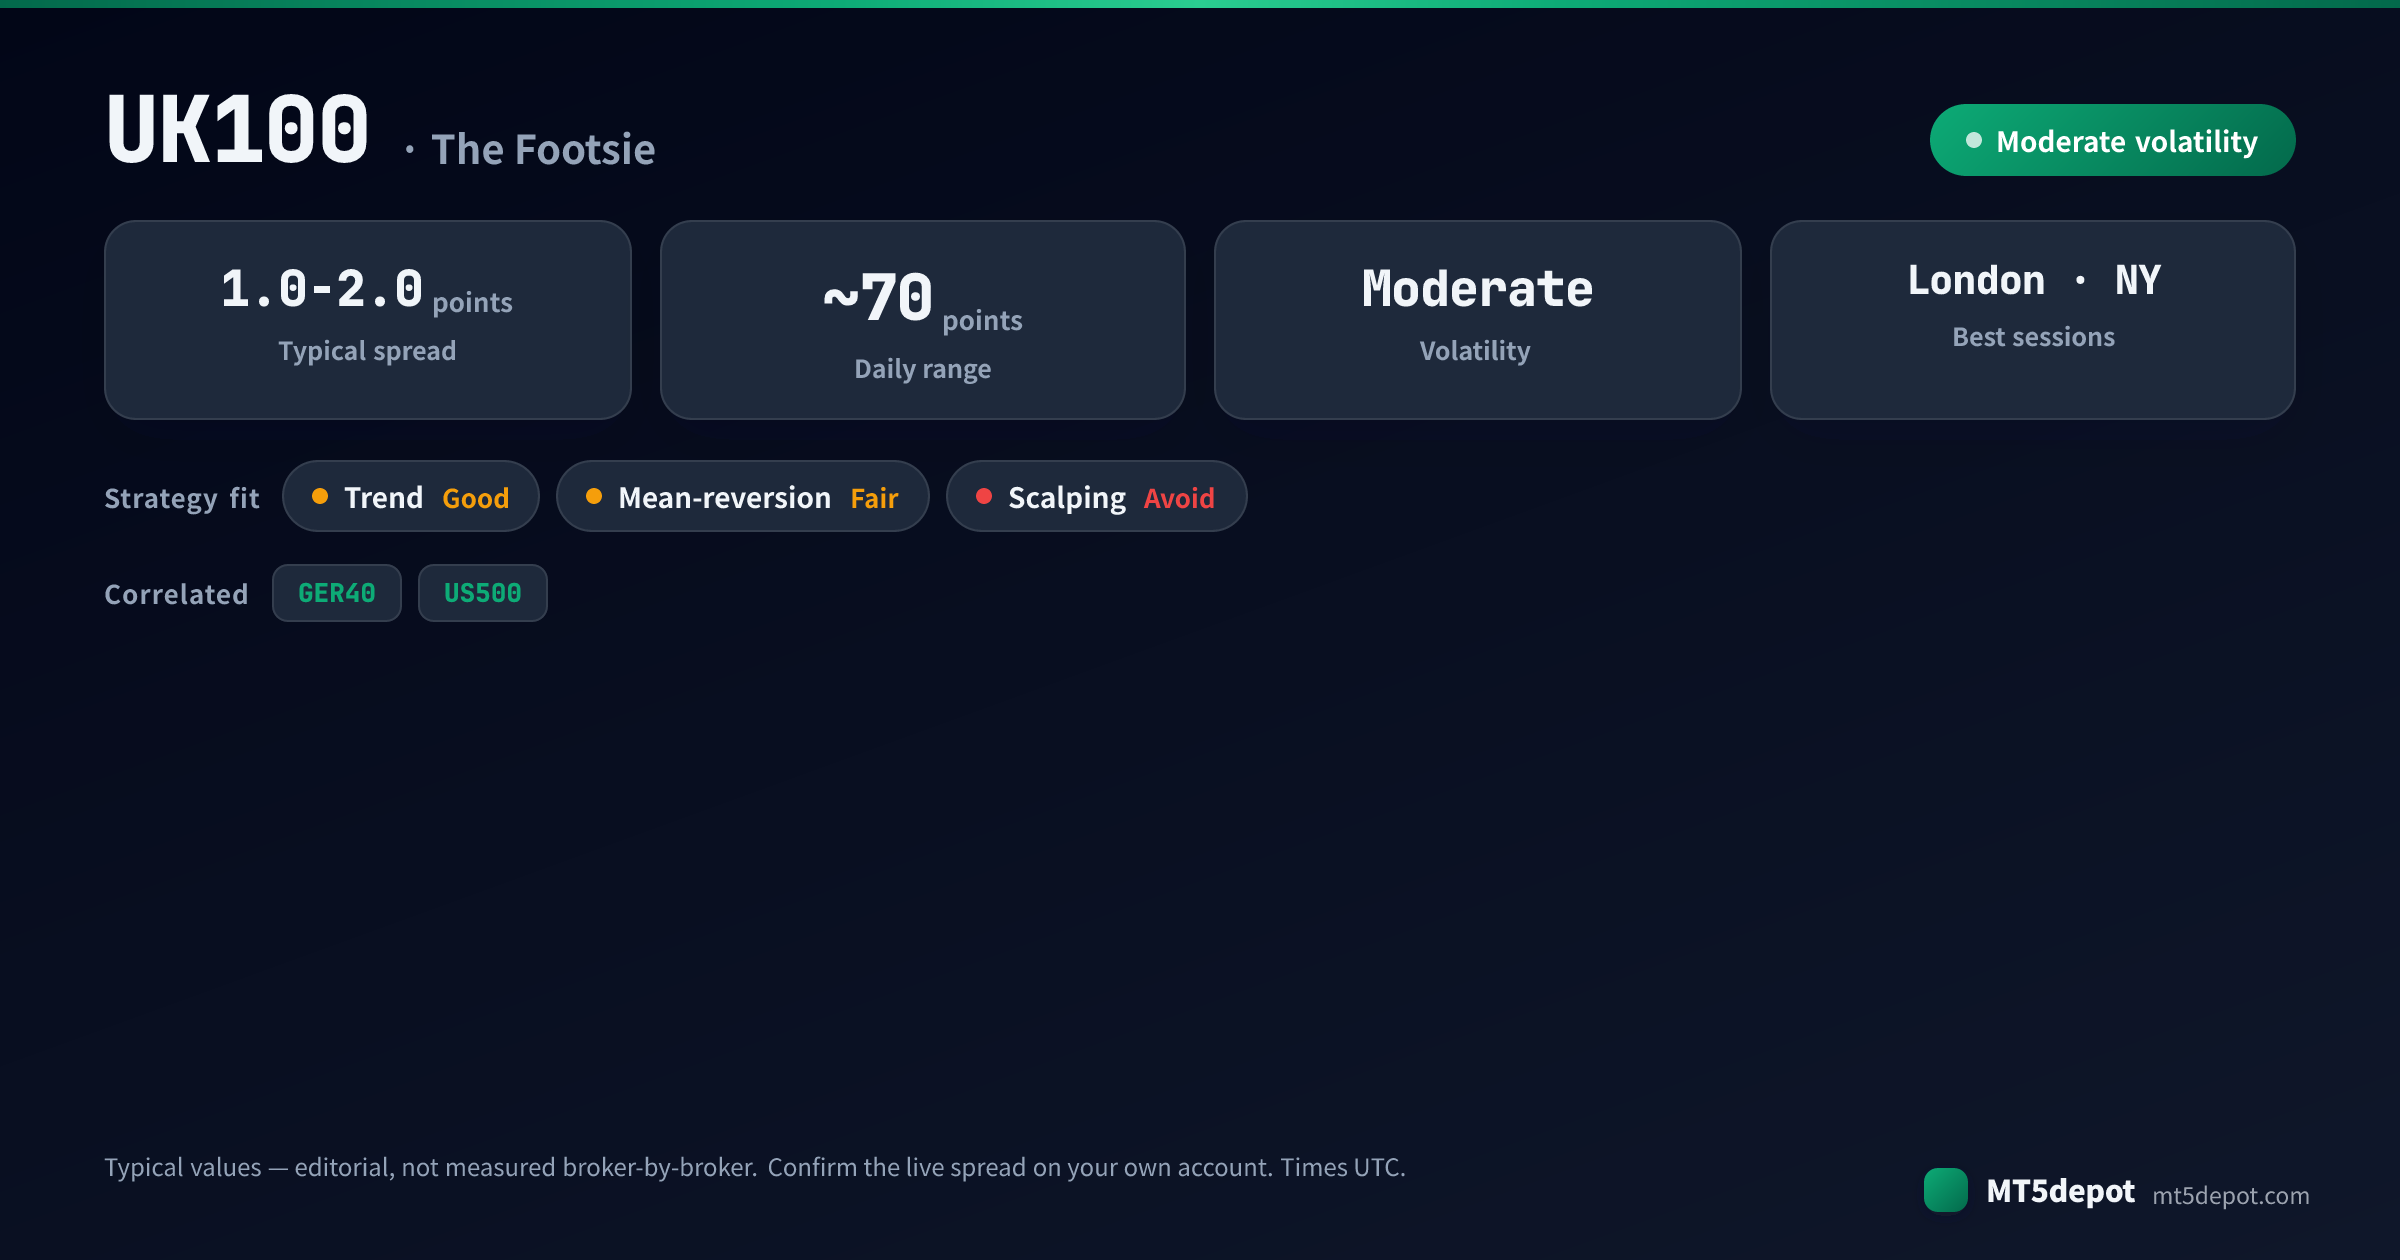
- Moderate volatility — calmer than the DAX. The index’s mature, large-cap, dividend-heavy composition tends to produce a narrower daily range than the more industrial GER40. Our published typical daily range is near 70 index points — labelled typical, not measured broker-by-broker. That gives trend systems a cleaner tape, but leaves mean-reversion systems less amplitude than a louder index offers.
The trap for automated strategies is that the Footsie’s calmer range looks like an easy trend market on a backtest. Its two hidden drivers — sterling and commodities — sit outside the price series an indicator reads, and its overnight gap sits outside the tick stream a forex EA assumes is continuous. UK100 rewards strategies that respect its volatility regime and its currency-and-commodity wiring, and quietly drains ones that treat it as a forex pair or the DAX with a different name.
Which EA Strategies Suit UK100?
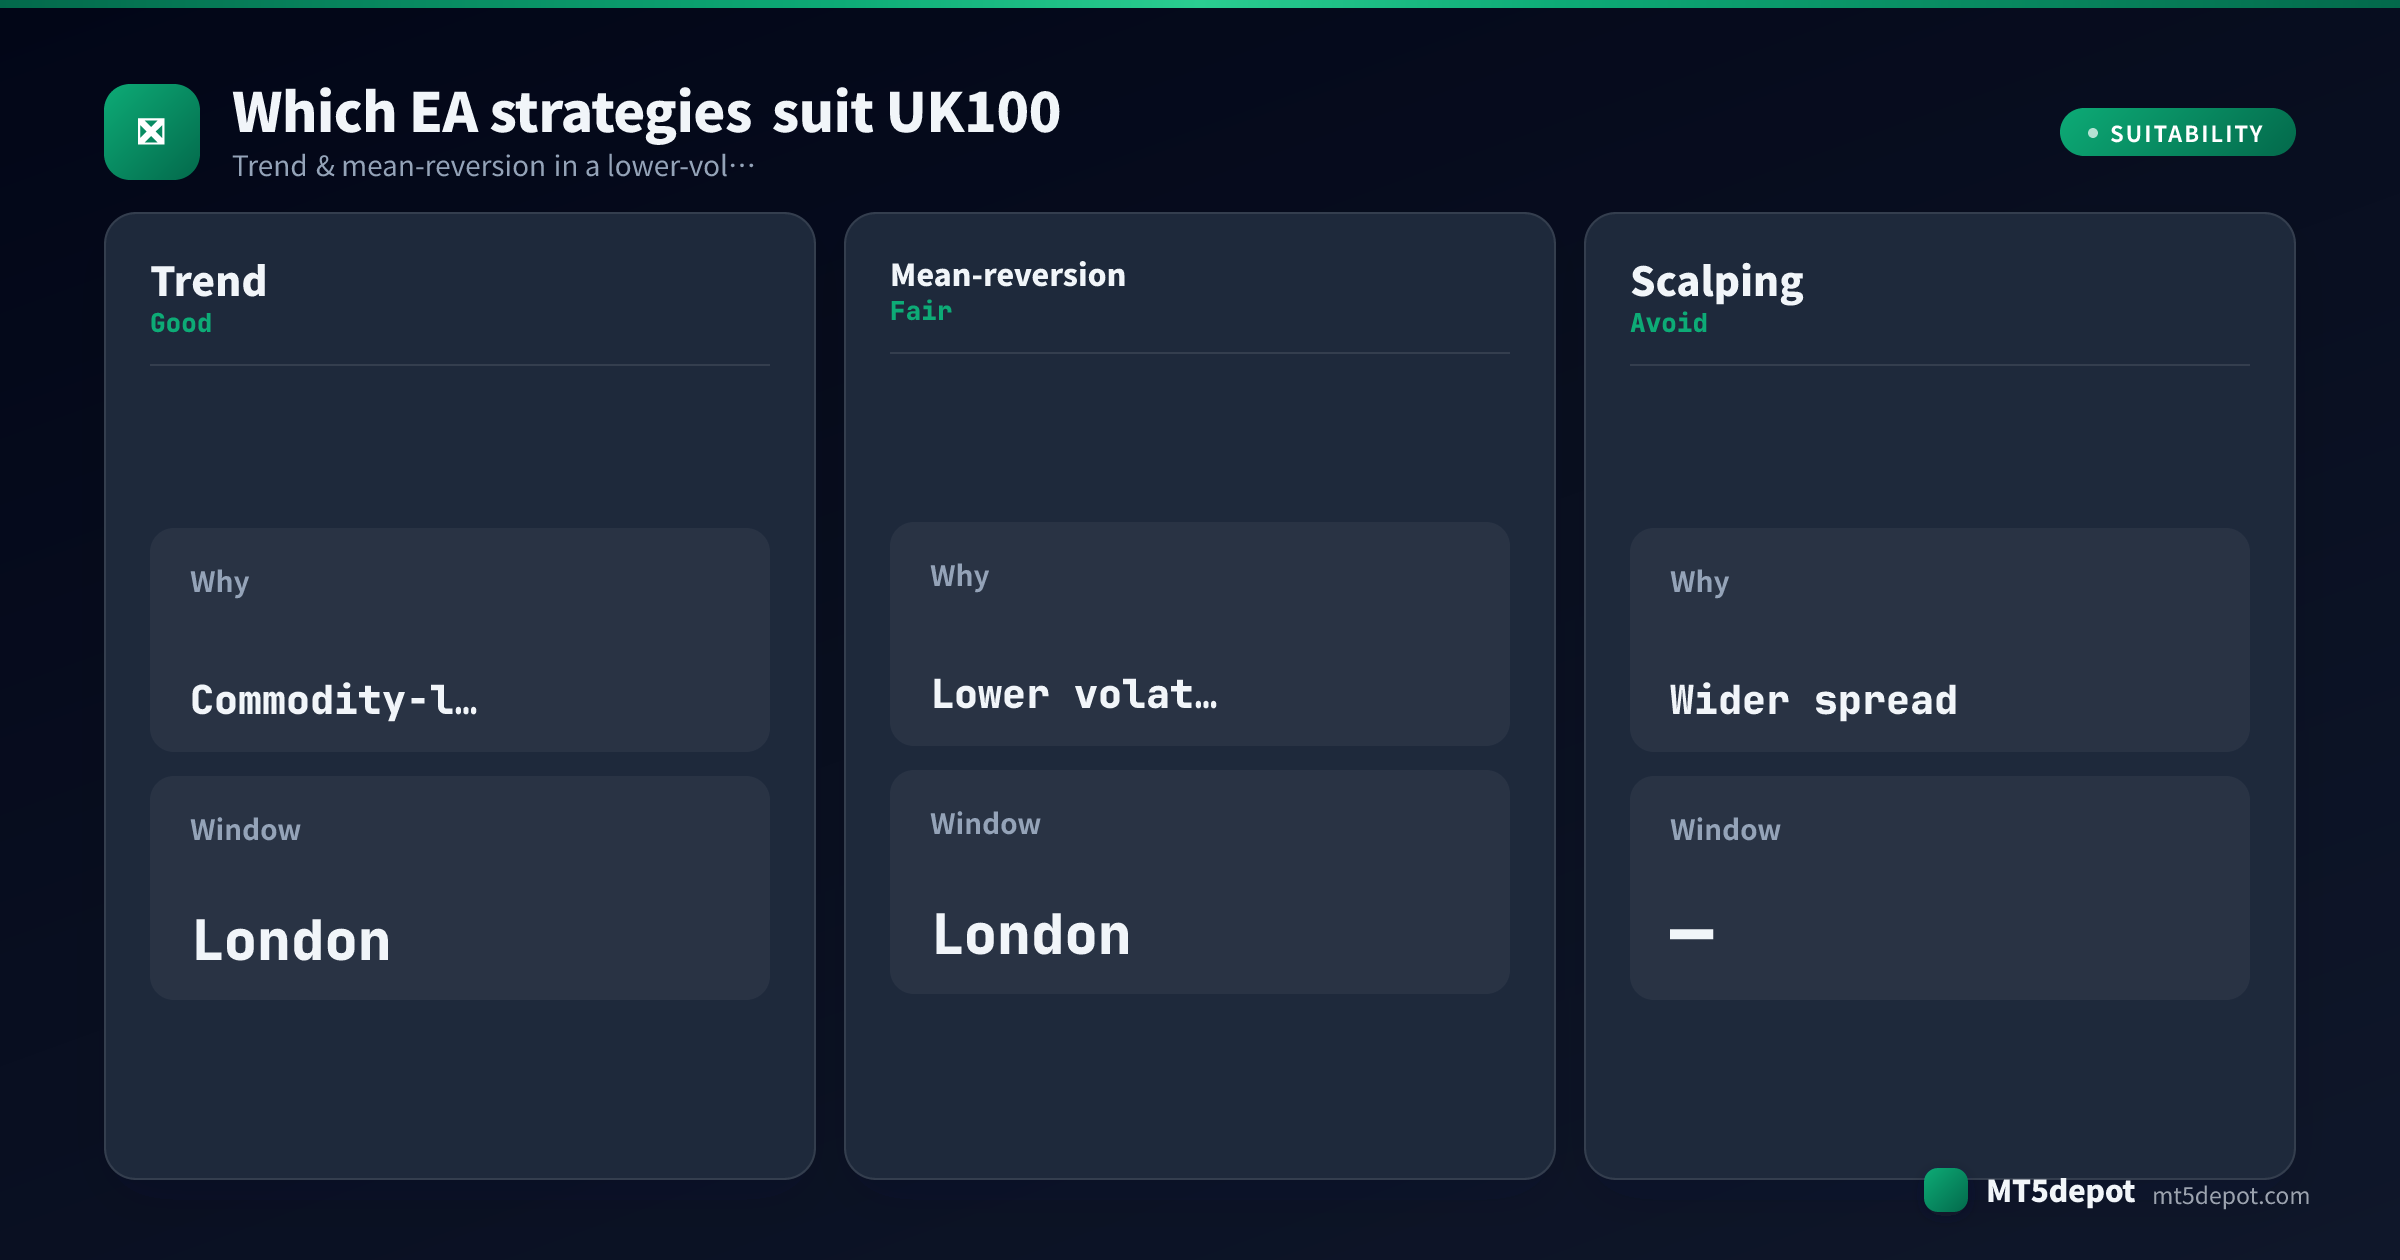
The instrument’s profile lists trend and mean-reversion as suitable — but suitability is an editorial assessment, not proof. In our own stock-settings baseline of the Strategy Builder’s templates — a single USD/JPY M5 run over one year, default inputs, no optimisation — most finished below a 1.0 profit factor, and that run was not on UK100. Almost none cleared the Strategy Builder’s own bar at stock settings, so treat any edge on UK100 as something your own settings and test have to earn. Look for it in session windows, higher-timeframe filters and gap-aware stops, not the indicator on the box. What the Footsie’s character tends to support:
| Strategy | Fit on UK100 | Why |
|---|---|---|
| Trend | Good | Commodity-led and sterling-driven moves give the index sustained directional runs through the London cash session. A trend EA that adds a commodity or GBP context filter has more to work with than one reading the index price alone. |
| Mean-reversion | Fair | The Footsie’s moderate volatility produces cleaner ranges than the DAX, which suits a fade — but the lower amplitude means smaller targets, so the spread and overnight financing eat a larger share of each trade. |
| Scalping | Avoid | The index-point spread is wide relative to a small intraday target, and the overnight cash-session gap means a scalper holding through a session boundary can be jumped rather than stopped. |
| Multi-index basket | Handle with care | UK100 is correlated with GER40 and US500 on risk tone, so a “diversified” book across them is closer to one leveraged bet than a hedge (covered below). |
Trend on the higher timeframes is the shape that turns the Footsie’s commodity-and-currency drivers into an asset. Mean-reversion fights the spread on smaller targets, and scalping fights both the spread and the gap. The practical route is to build one of these shapes yourself. The Strategy Builder ships templates that accept index CFDs and exposes every parameter, including stop and target sizing in points — then test it (below) before you trust a single number.
Best Trading Hours for UK100 EAs
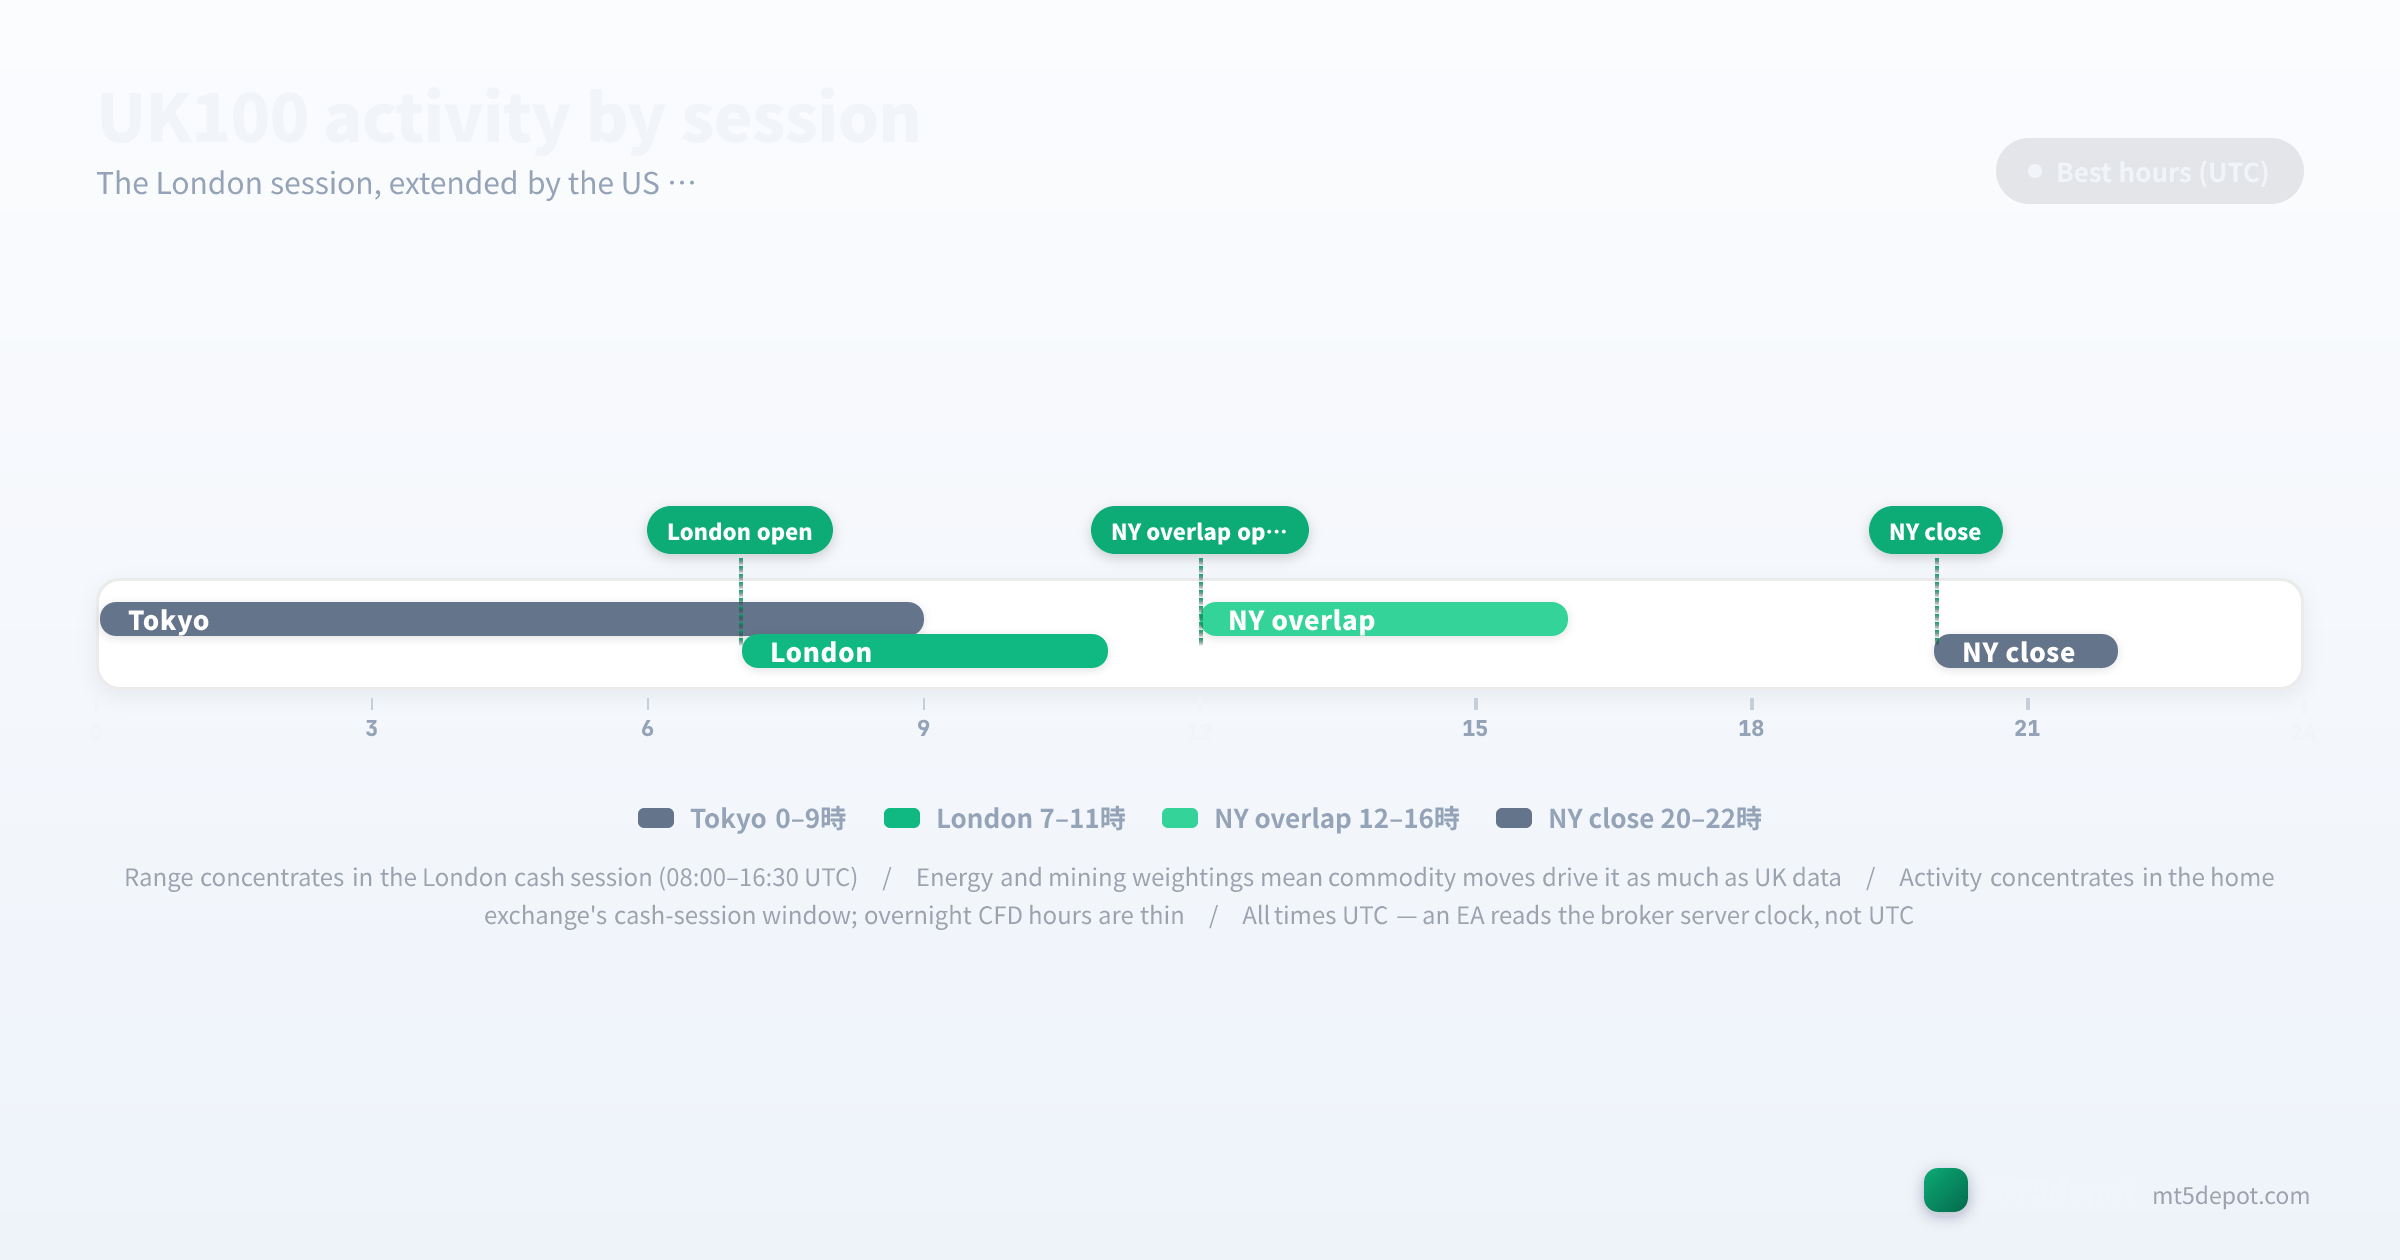
Session structure decides more of a Footsie result than indicator choice does. Unlike a 24-hour forex pair, the index has a hard cash-session frame:
- Pre-open / overnight (before 08:00 UTC): thin liquidity, with much of the price discovery happening off the cash market. Any position carried here faces the reopening gap rather than a continuous tape — this is where the cash-session gap risk lives, and a session filter is right to exclude it.
- London cash session (08:00–16:30 UTC): the primary window. The FTSE 100’s range concentrates here, sterling and commodity moves feed directly into the index, and UK100 EAs tend to earn most of their result in these hours.
- US open overlap (roughly 13:30–16:30 UTC): the second momentum window. When Wall Street opens, US risk tone and dollar moves add a driver on top of London. This stretch is often the most active of the day, and where the correlation with US500 is strongest.
- After the London cash close (after 16:30 UTC): liquidity fades and the price heads toward the next overnight gap; slower EAs should plan exits around this boundary rather than trading through it.
In our editorial assessment, EAs that restrict trading to the London cash session and the US overlap often out-perform round-the-clock variants on the Footsie. Treat a session filter as part of the strategy definition rather than an optimisation flourish. Two cautions come with it. Scheduled BoE decisions and UK data prints sit inside the London window and widen the index spread exactly then, so a fast strategy needs a news pause. And every clock time above is UTC. An EA reads your broker’s server clock, which is usually not UTC, so an “08:00” London-open filter shifts silently when you move the EA between brokers on different server timezones. Verify it once in MT5’s Market Watch, and every session boundary lines up.
Spreads, Costs, and Execution
An index CFD is costed differently from a currency pair: UK100’s three cost layers — spread, commission and overnight financing — all interact with its point value. The figures below are editorial reference ranges from broker-published index-CFD conditions (updated July 2026), quoted in index points, not forex pips, and not broker-by-broker measured numbers. Confirm the live spread and point value on your own account before you size a fast strategy:
| Cost component | Typical UK100 figure | Applies when | Note |
|---|---|---|---|
| Spread | 1.0 – 2.0 points | every trade | widens around BoE / UK data and outside the cash session |
| Commission | $0 (built into spread) or per-contract | raw-type index accounts | an account property, not an instrument property |
| Overnight financing | debit/credit at daily rollover | any position held past the cash close | erodes a slow long trend; can pay a short |
Two cost rules specific to this instrument:
- Cost is in points, and the point value is set by your account. A UK100 “point” converts to account currency by a contract-defined point value that varies by broker and lot size. The dollar cost of a 1.5-point spread is therefore not fixed the way a EUR/USD pip roughly is. Confirm your point value before you translate any backtest cost into money.
- Overnight financing is a real drag no FX cost model includes. As a cash-index CFD, a position carried past the daily rollover pays or receives financing, so a slow long-only trend EA quietly bleeds a small amount every night it holds. A strategy validated with financing switched off is running different economics from the live version.
Risks to Test Before Going Live
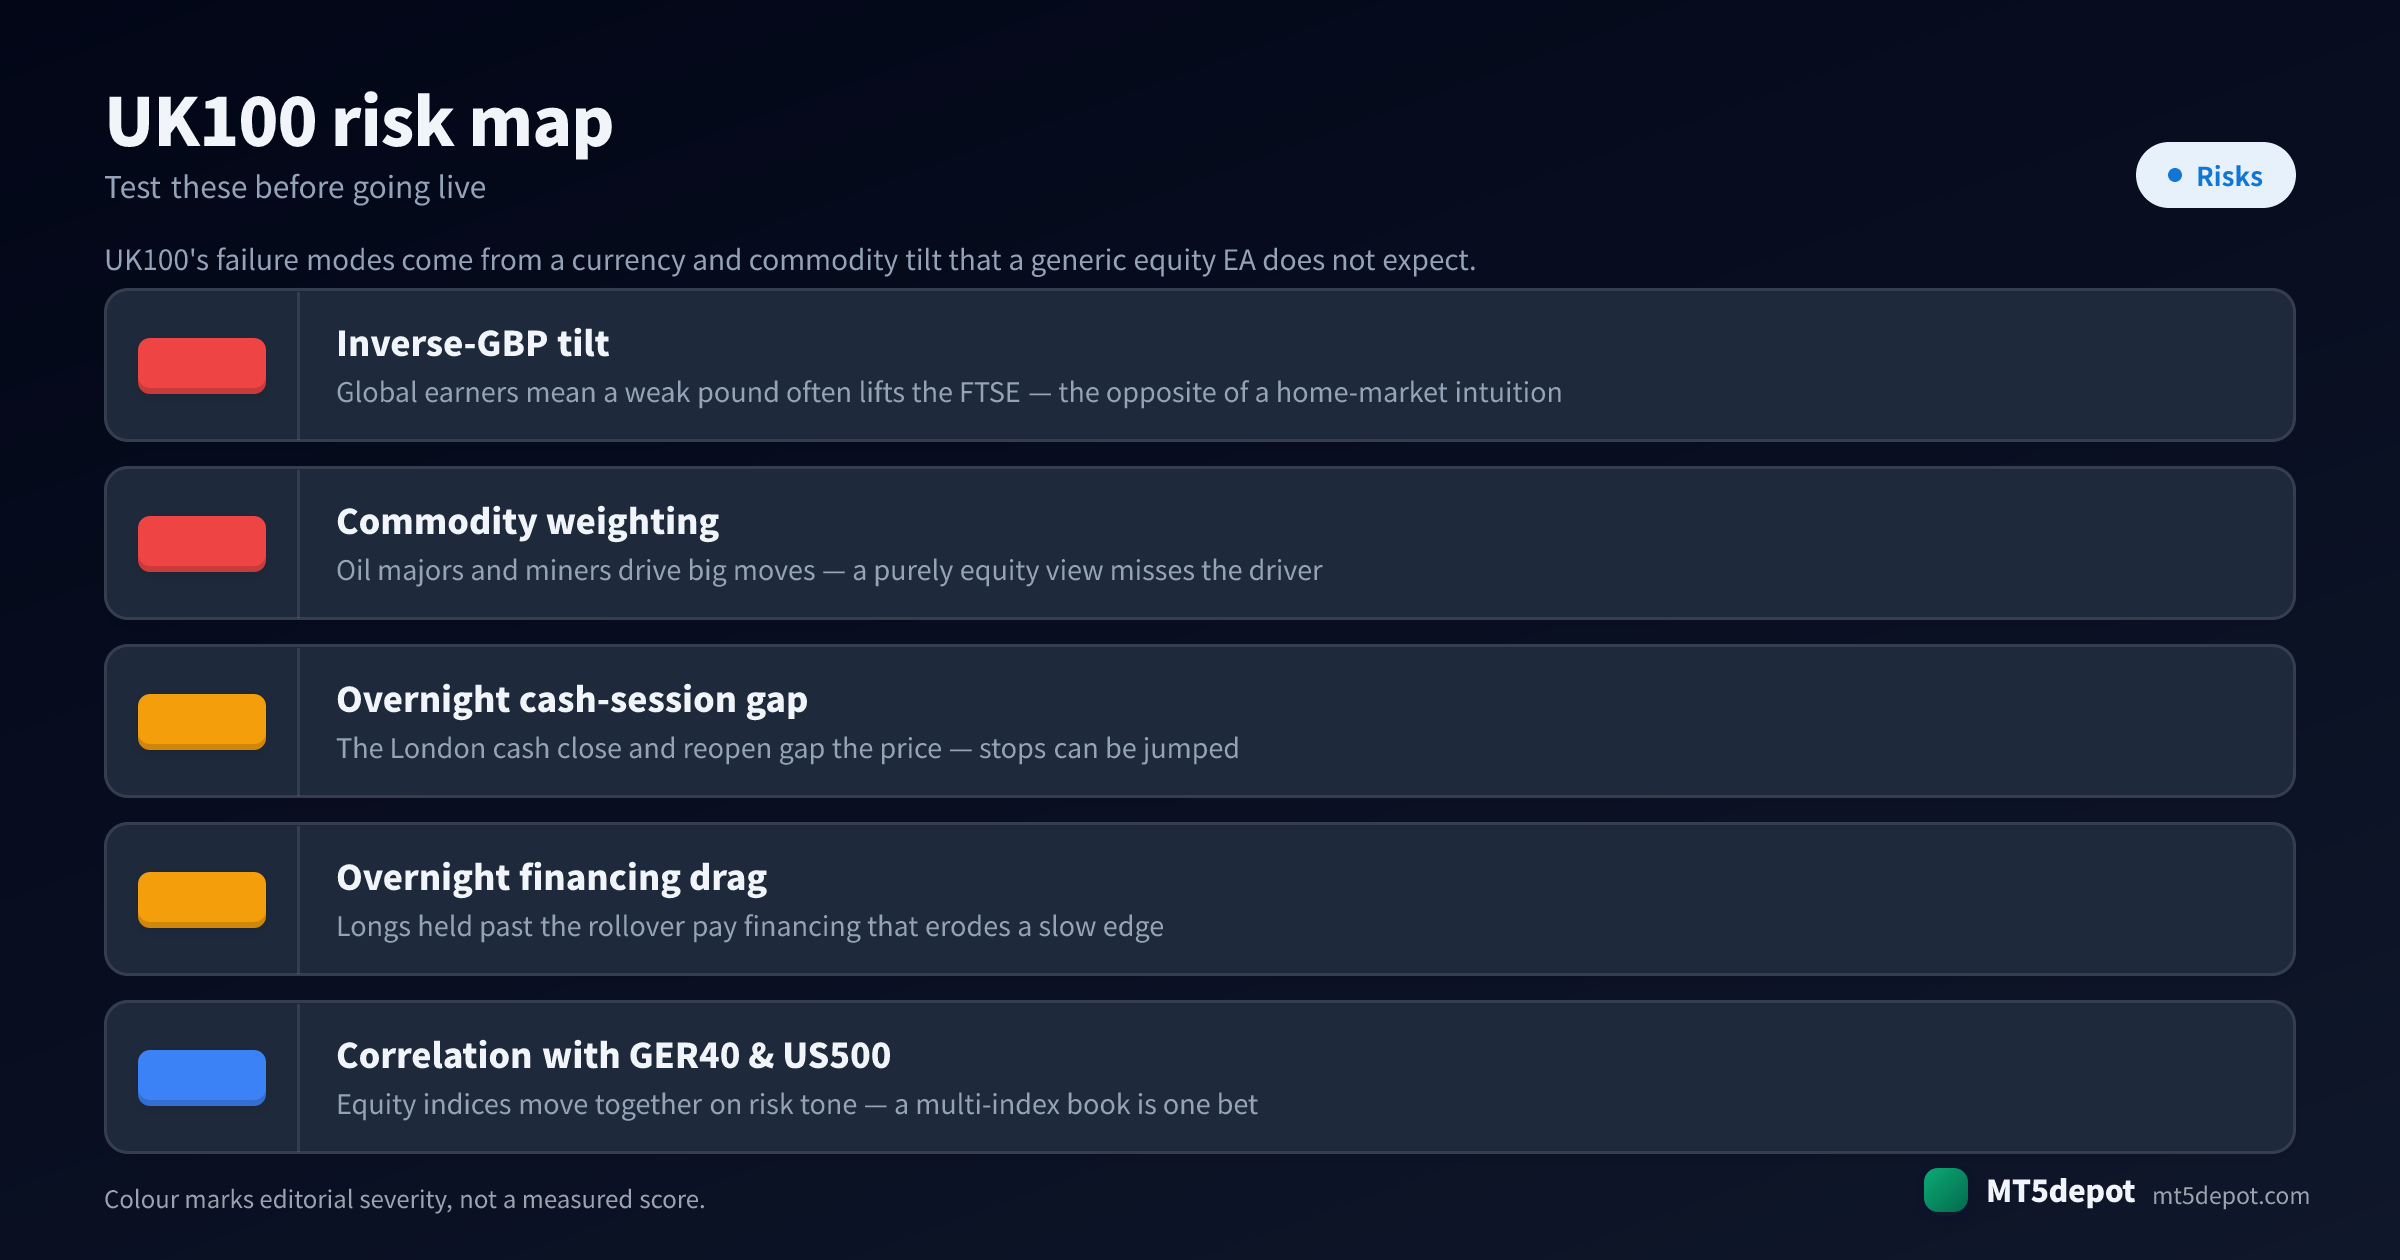
The Footsie’s failure modes come from a currency-and-commodity tilt and an index-CFD structure that a generic equity or forex checklist does not expect:
- The inverse-GBP tilt reverses the home-market assumption. A strategy that buys UK “strength” on a strong pound is often trading the wrong way, because a weaker sterling tends to lift the globally-earning index. An EA reading price alone cannot see this driver, so a trend system can hold straight through a sterling-led reversal. Test across periods of both a rising and a falling pound before trusting it.
- Commodity moves drive the index from outside the price series. Oil and metals headlines move the heavy energy and mining weightings, so a UK100 EA can be blindsided by a commodity catalyst with nothing on the UK data calendar. A price-only strategy has no filter for the thing that most often moves it.
- The overnight cash-session gap jumps stops. The London cash close and reopen gap the price rather than trading through it. A stop inside that gap is filled at the reopening level, not the stop level — a slippage mode a continuously-traded forex EA never models. Any overnight position needs stops sized for a gap, not a tick.
- Overnight financing erodes a slow edge. Longs held past the daily rollover pay financing that accumulates against a low-turnover trend strategy. A per-night cost that never appears in a financing-off backtest can turn a marginally positive strategy negative live.
- Correlation with GER40 and US500 is hidden leverage. Equity indices move together on shared risk tone, so two “diversified” EAs on UK100 and GER40 are closer to one leveraged position than a hedge. The correlation doubles your exposure without appearing in either EA’s risk settings, and it is tightest during the US overlap.
How to Test a UK100 EA
On the Footsie, the test is the whole edge. Hold anything you build to the bar set out in the site’s methodology:
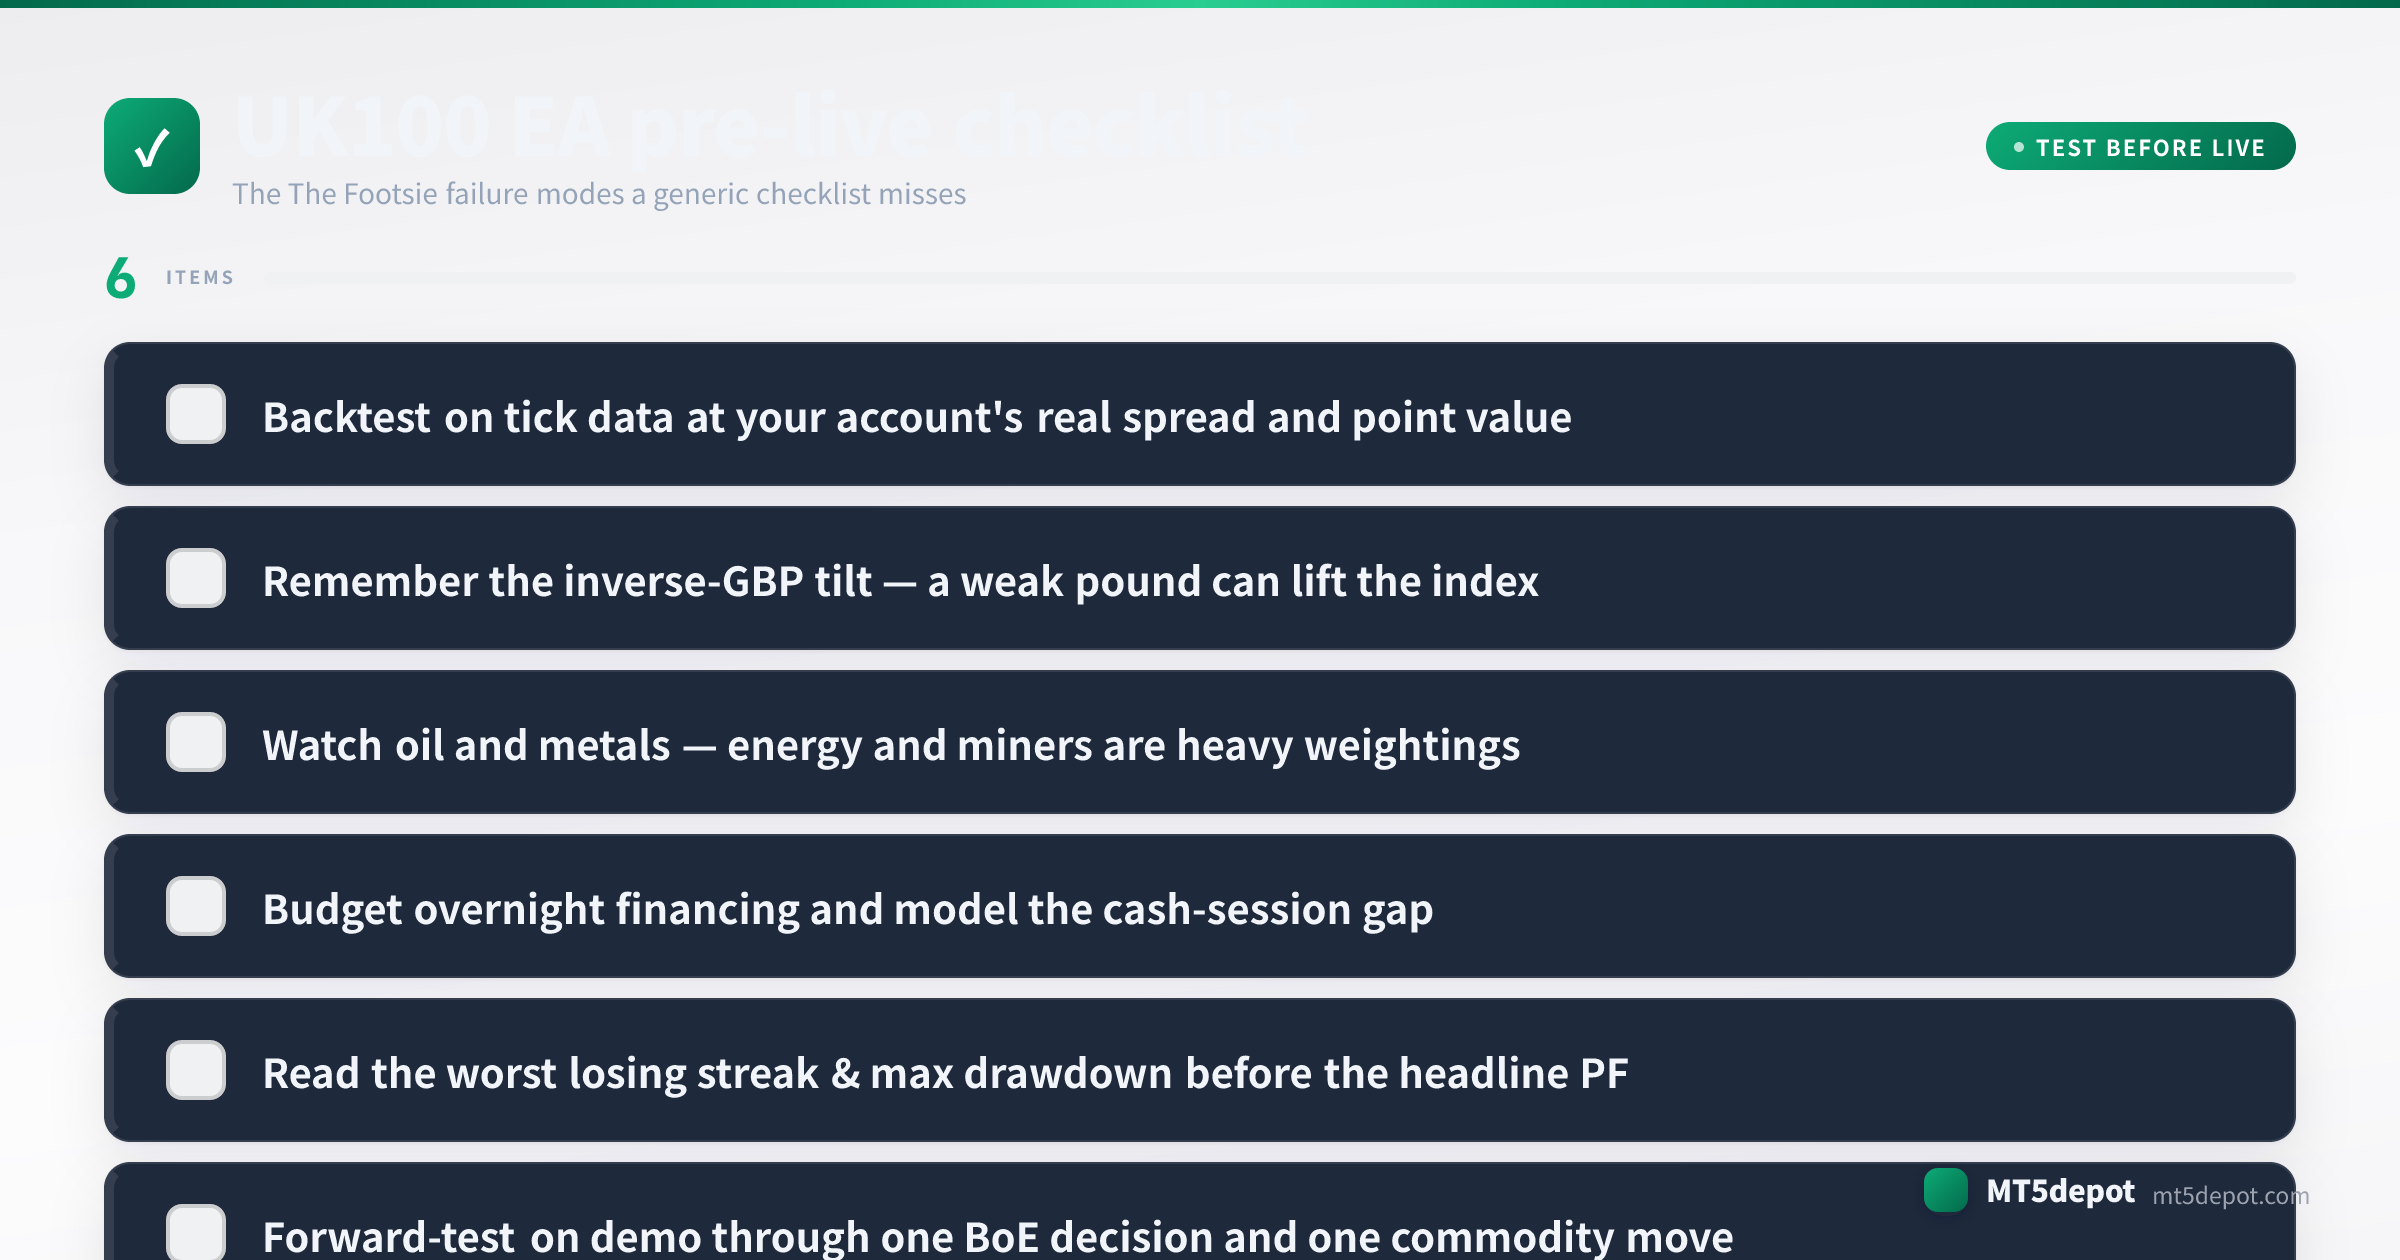
- Backtest on tick data at your account’s real spread, point value and financing. Use an every-tick model with the 1.0–2.0-point spread you will actually trade, your account’s point value, and overnight financing switched on — not the platform defaults. On an index CFD that financing gap is real account currency.
- Read the worst losing streak in account-currency terms. Convert the max drawdown and longest run of losing trades from index points into money using your point value, because a modest point drawdown can be a larger capital one depending on lot size.
- Forward-test on demo through one BoE decision and one commodity move. UK100’s defining risks — the sterling tilt and the commodity weighting — only show up around those catalysts. A demo window that never spans a rate decision or an oil/metals swing has not tested what matters most, and a window spanning an overnight gap is worth waiting for too.
- Confirm the server clock before the first live trade. Re-check MT5’s Market Watch time against the UTC session hours above, and again after any broker migration. Easy to skip, expensive to miss when your session filter is anchored to the London cash open.
Every backtest number this produces is a historical measurement, not a forecast — size for the drawdown you measured rather than the return you hope for.
UK100 EAs and Strategy Builder Templates
We have not published a UK100 backtest of our own, and a forex or DAX result does not carry over to an index wired inversely to sterling and driven by oil and miners. The honest route to a UK100 EA is to build and verify one:
- The Strategy Builder (open it here) accepts index CFDs in its trend and mean-reversion templates and exposes every parameter — crucially stop and target sizing in index points. The EA you deploy is built on your own gap-and-financing assumptions.
- Broker and account fit. A UK100 CFD’s spread, point value and financing depend on the account. Check those on your own broker before sizing anything — index-CFD terms differ more between brokers than forex spreads do.
- The concept canonicals. If a term above is unfamiliar, the volatility, ATR and leverage entries define the mechanics a Footsie EA depends on most.

